
One Article to Understand | 2025 Performance Ranking of All Listed Companies in China's Lighting Industry Chain!
As ofApril 30, 2026, the 2025 annual report performance of listed companies related to China's lighting industry chain has been released successively.This article compiles99A-share listed companies,8H-share listed companies and78New Third Board listed companies etc., totaling185companies' annual report performance.We carefully extracted their business situations related to the lighting industry chain and made relevant performance rankings for reference. Although it is but a glimpse through a tube, one leaf can reveal the autumn; yet we strive not to be blinded by a single leaf.
(Note:Bdenotes Beijing Stock Exchange enterprises,Hdenotes Hong Kong Stock Exchange enterprises,Xdenotes New Third Board enterprises, whereCin the New Third Board denotes Innovation Layer enterprises)
Lighting Finished Products Sector
Lighting Finished Products Business Overview (Click to view large image) (Click to view larger image) 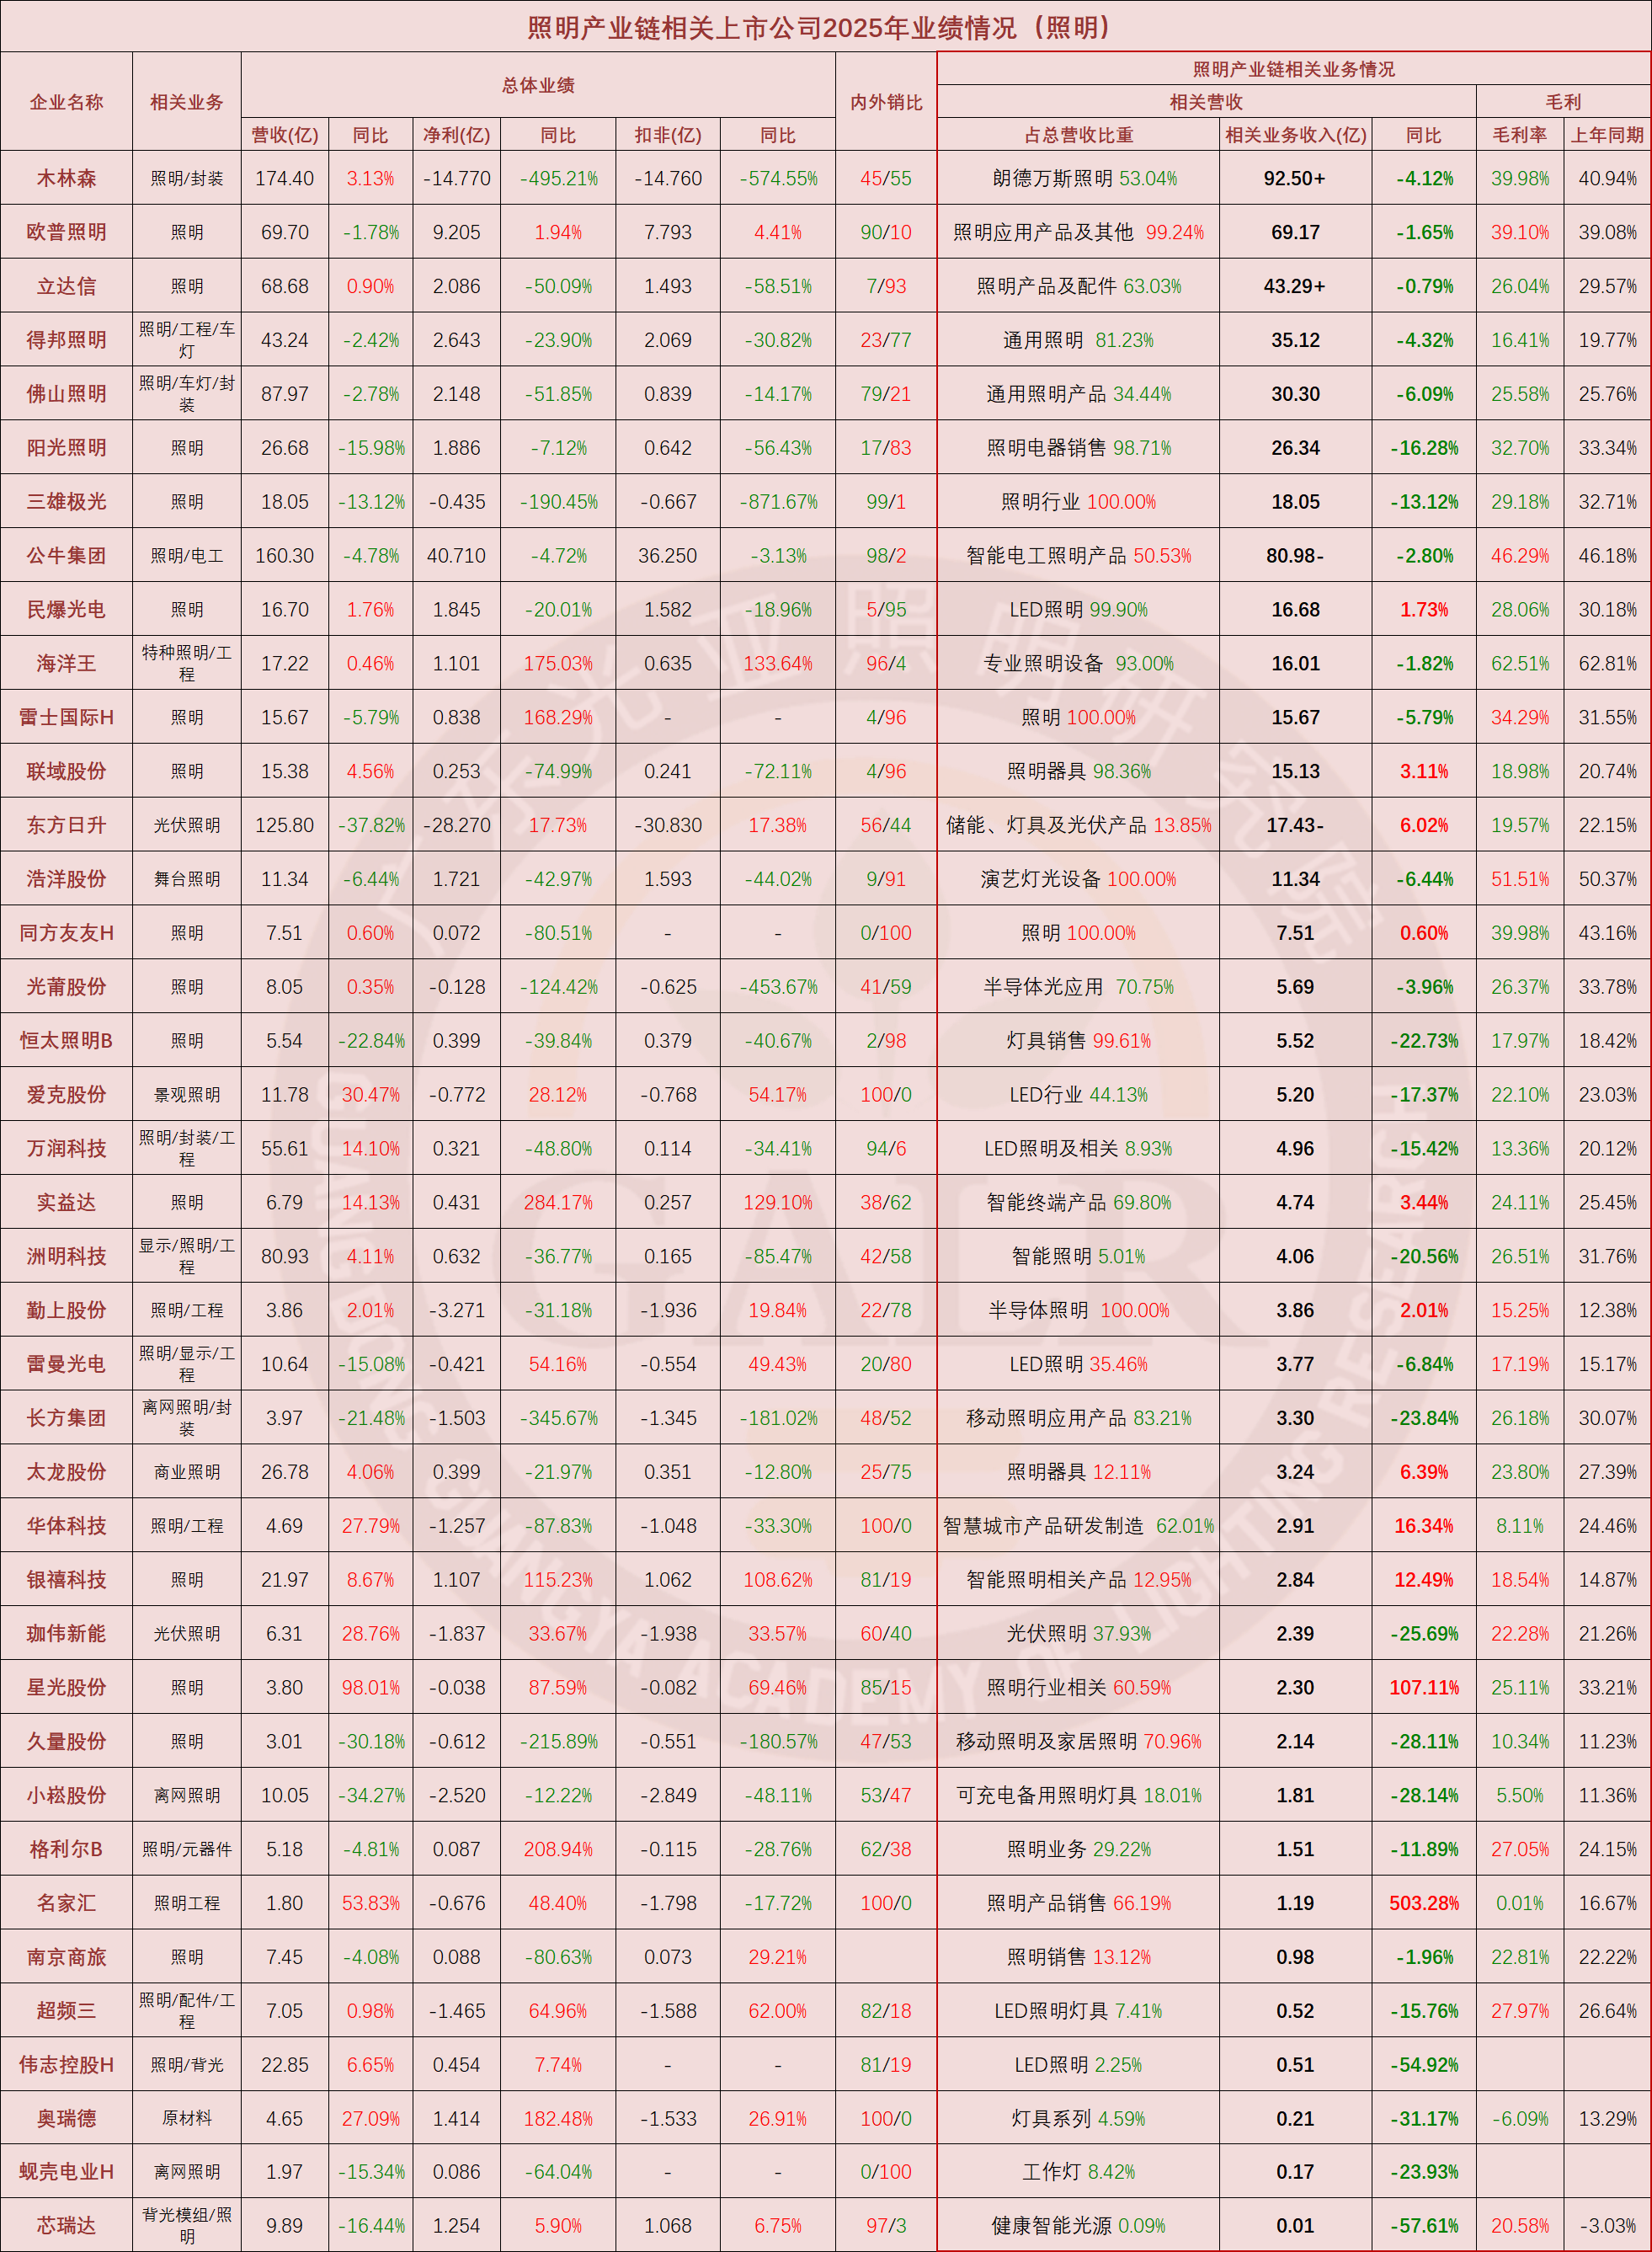
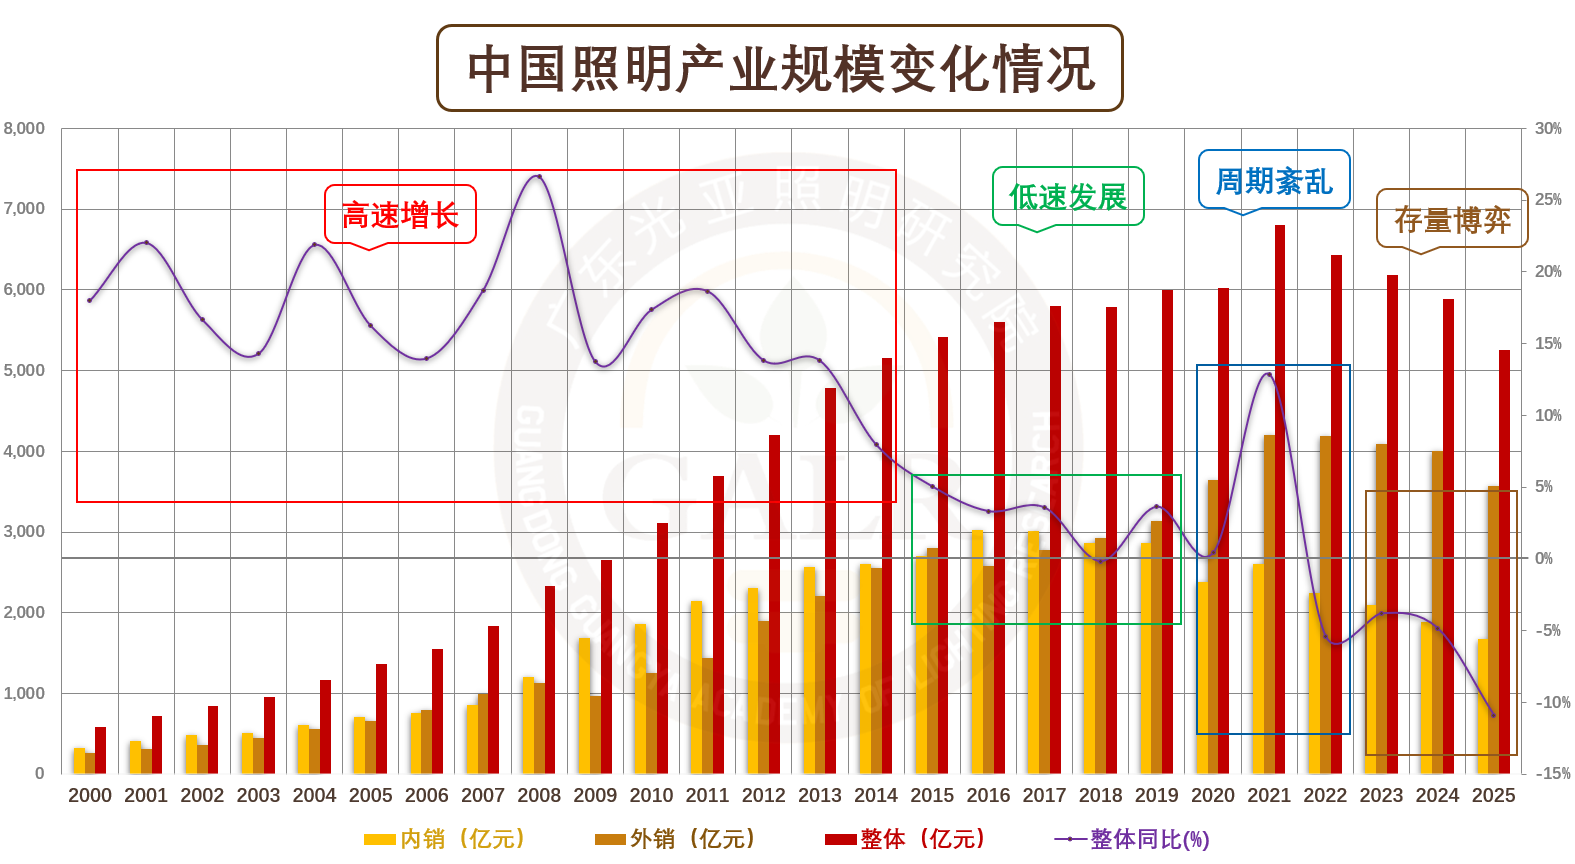
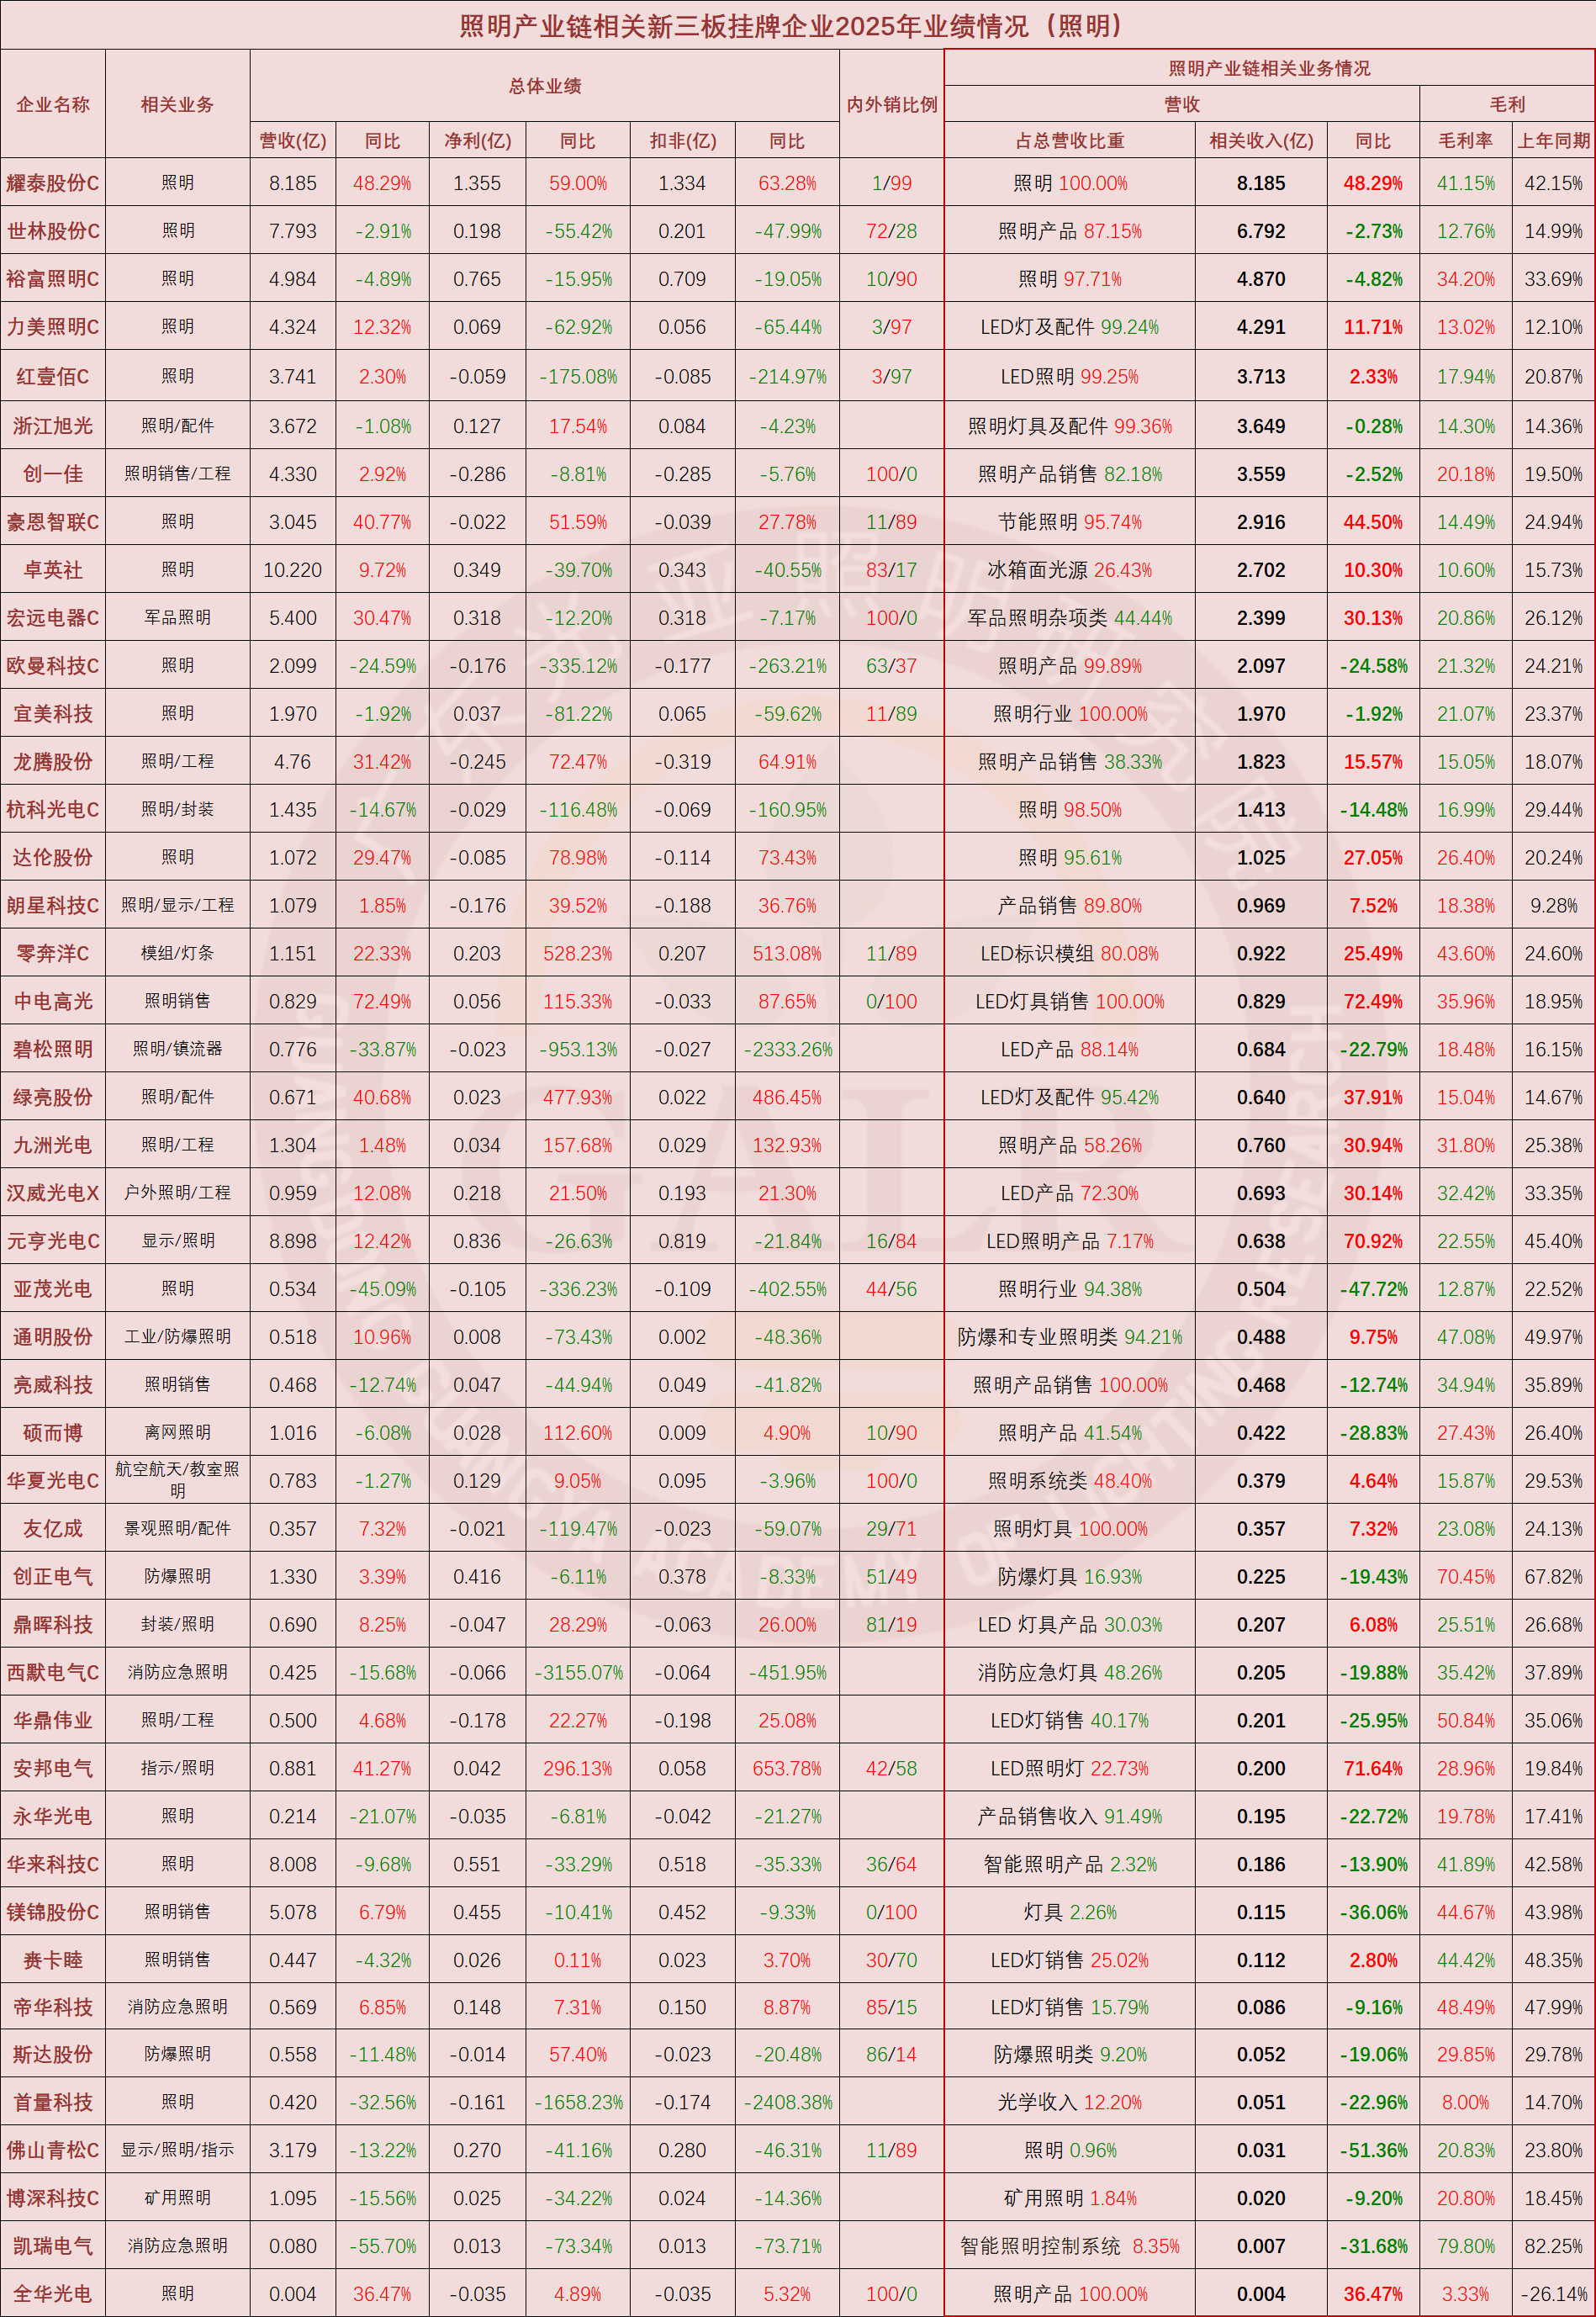
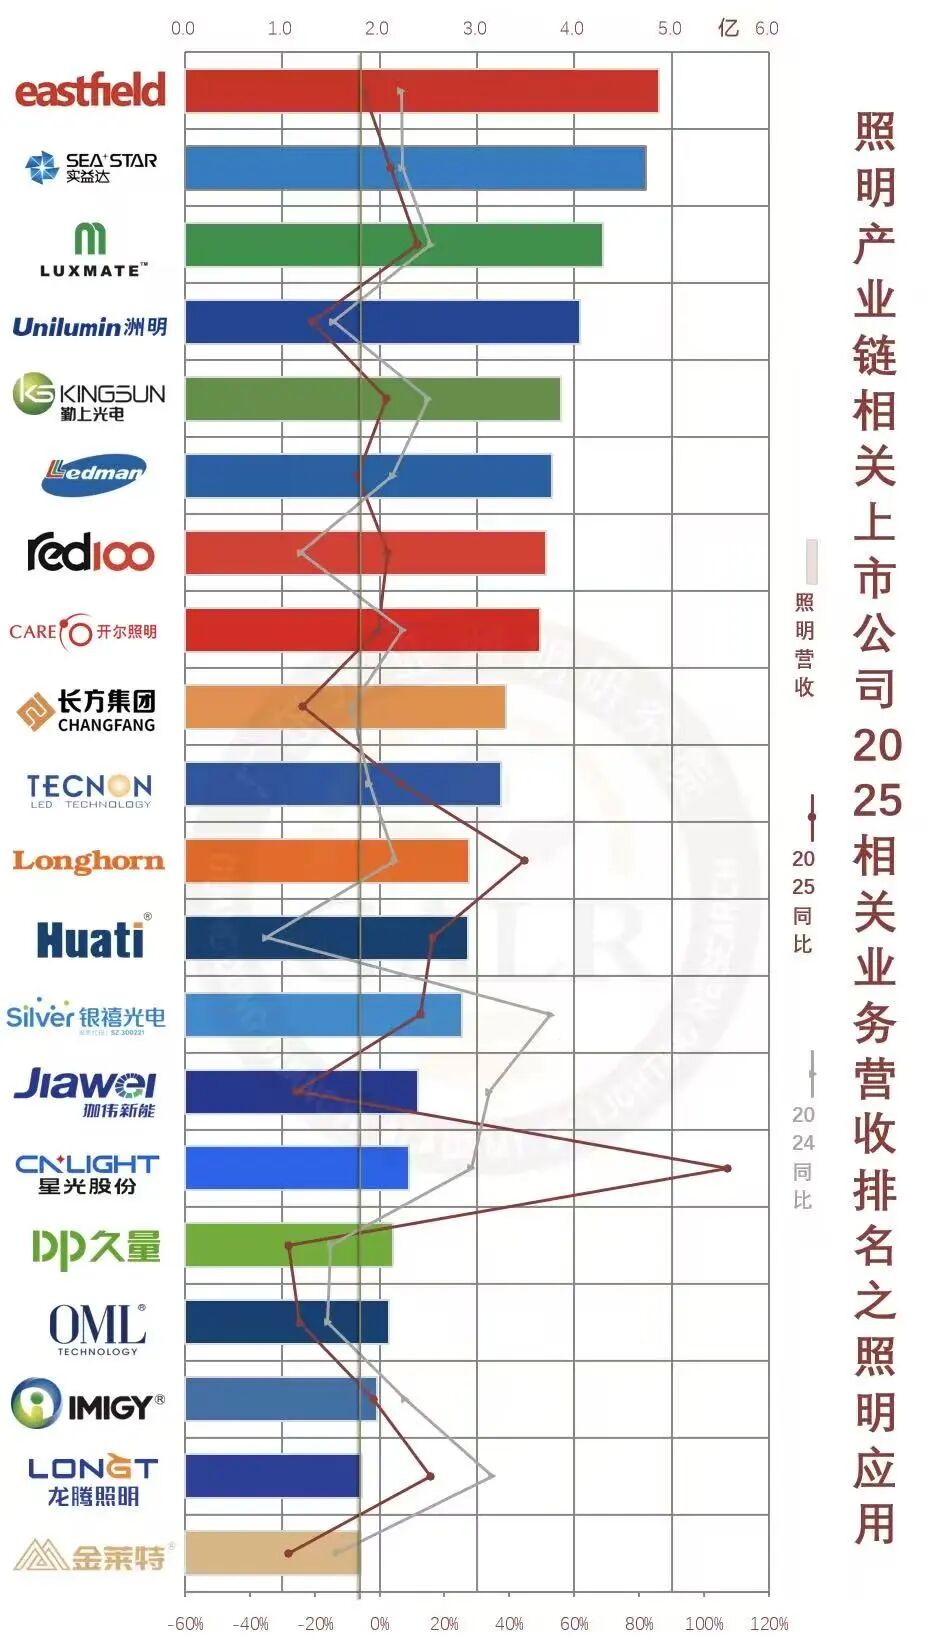
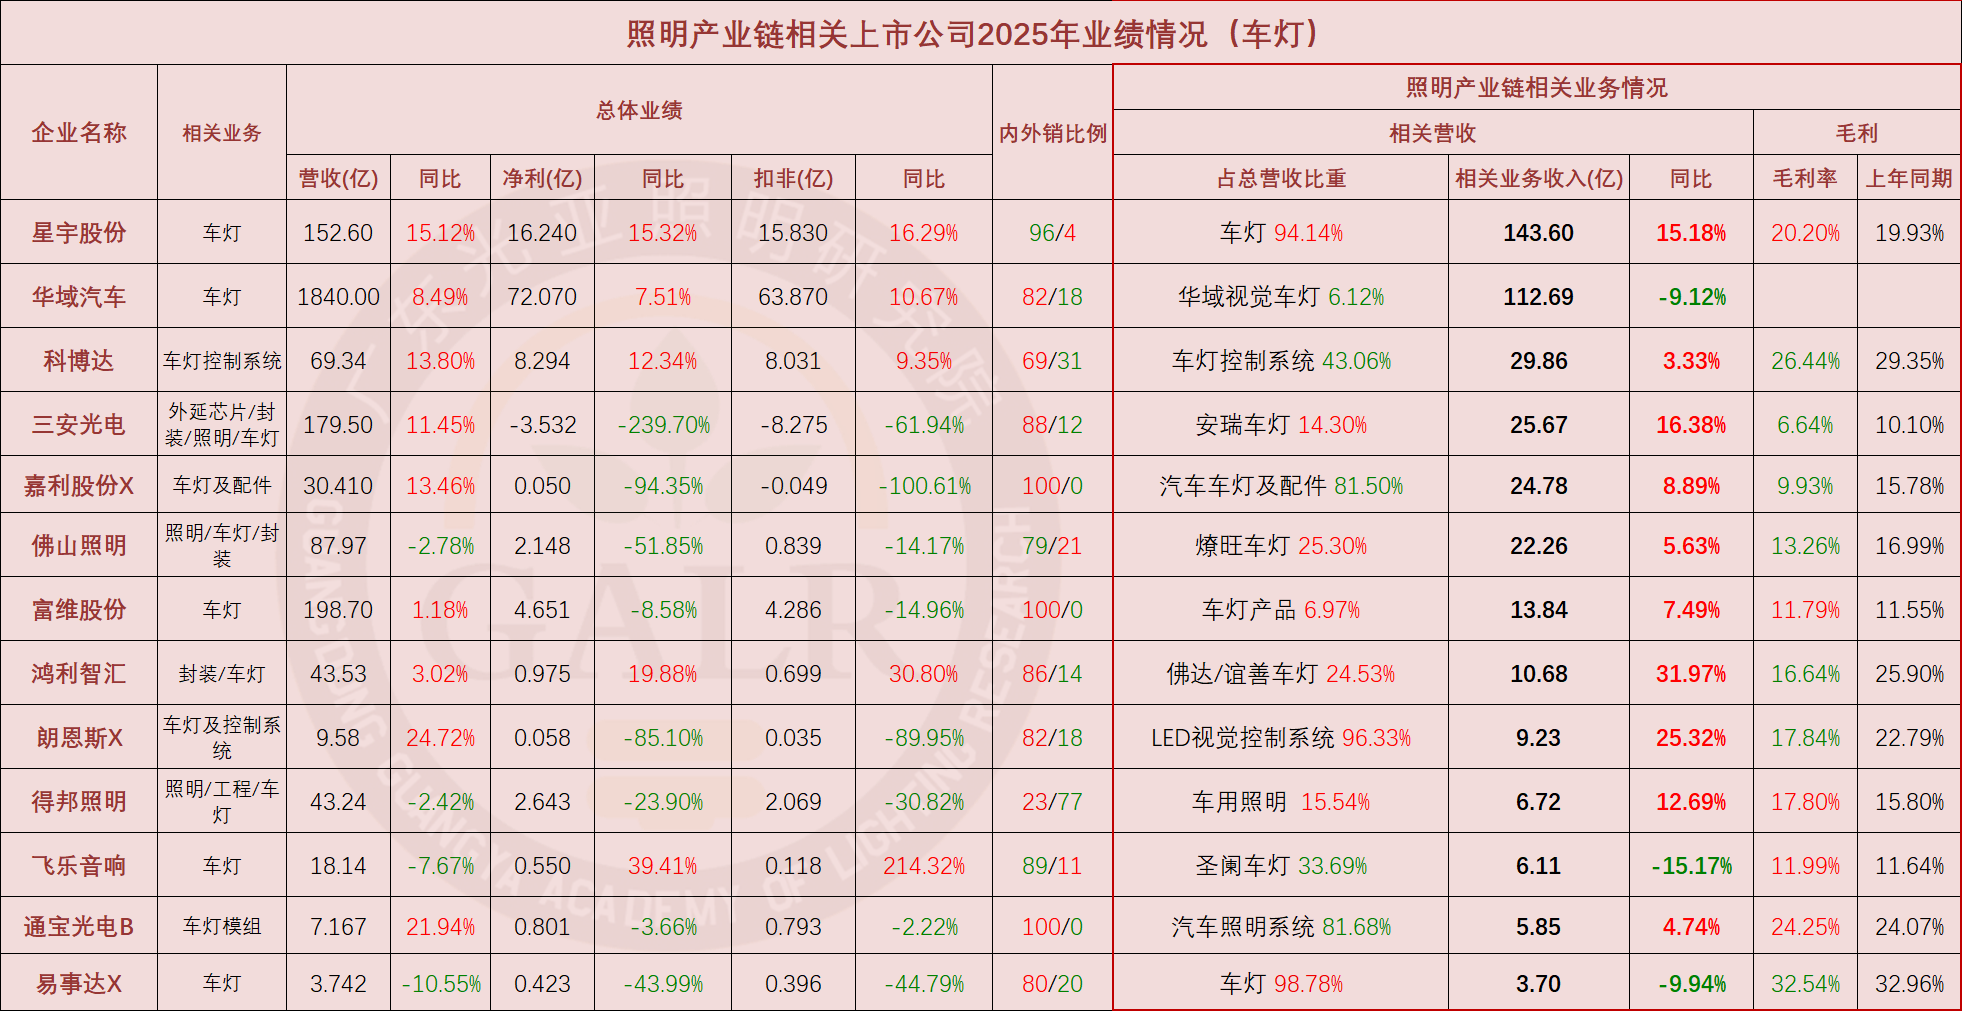
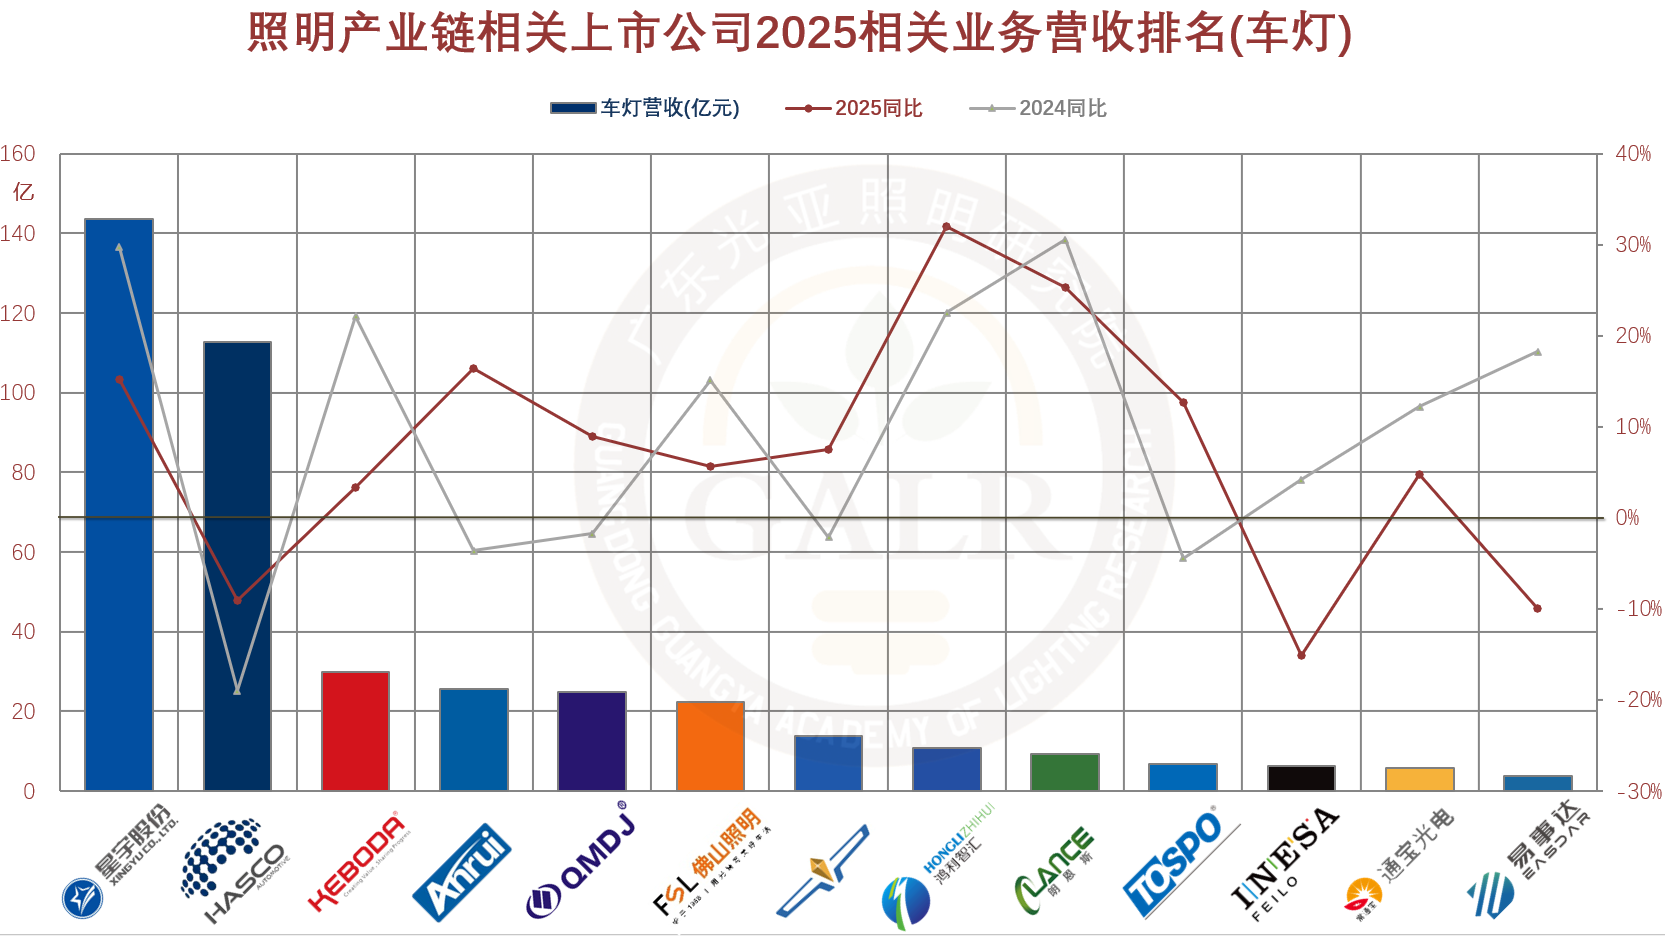
Lighting business overall ranking (top 40) (Click to view larger image) (Click to view larger image) Finished Lighting Products SegmentTop 40 Enterprises in Revenue Ranking for Lighting-Related Business in 2025, with combined revenue of approximately 53.4 billion yuan, accounting for 10.2% of the entire Industry scale. Industry concentration increased by 0.6 percentage points compared to the same period in 2024. Among them, 80% of enterprises had lighting-related business revenue growth lower than that of the same period in 2024, putting significant pressure on overall performance. 车灯板块 车灯业务排名 (Click to view full size) 车灯板块,2025年在新能源汽车大风口的加持下营收普涨,但利润滑坡不容小觑。 Among a total of 13 listed companies (including those on the New Third Board): Companies with growth in revenue from automotive lighting-related businesses accounted for 77%, an increase of 14 percentage points compared to the same period in 2024. Total revenue from automotive lighting was approximately 41.5 billion yuan, representing a year-on-year (YoY) growth of 5.1%. It is also important to note that the automotive lighting sector is highly competitive; specifically, the gross margin for front-mounted lighting assemblies is relatively low, lower than that of automotive lighting control system businesses (such as Keboda and Langens), and rear-market lighting businesses (such as Yishida), and significantly lower than the average gross margin of the general lighting segment. In 2025, companies experiencing a decline in gross margin for automotive lighting-related businesses accounted for 62%, with the average gross margin falling to 17.4%, a decrease of up to 2.3 percentage points compared to the same period in 2024; Ranking of automotive lighting businesses (Click to view large image) LED Packaging Segment Packaging Business Status (Click to view large image) (Click to view large image) 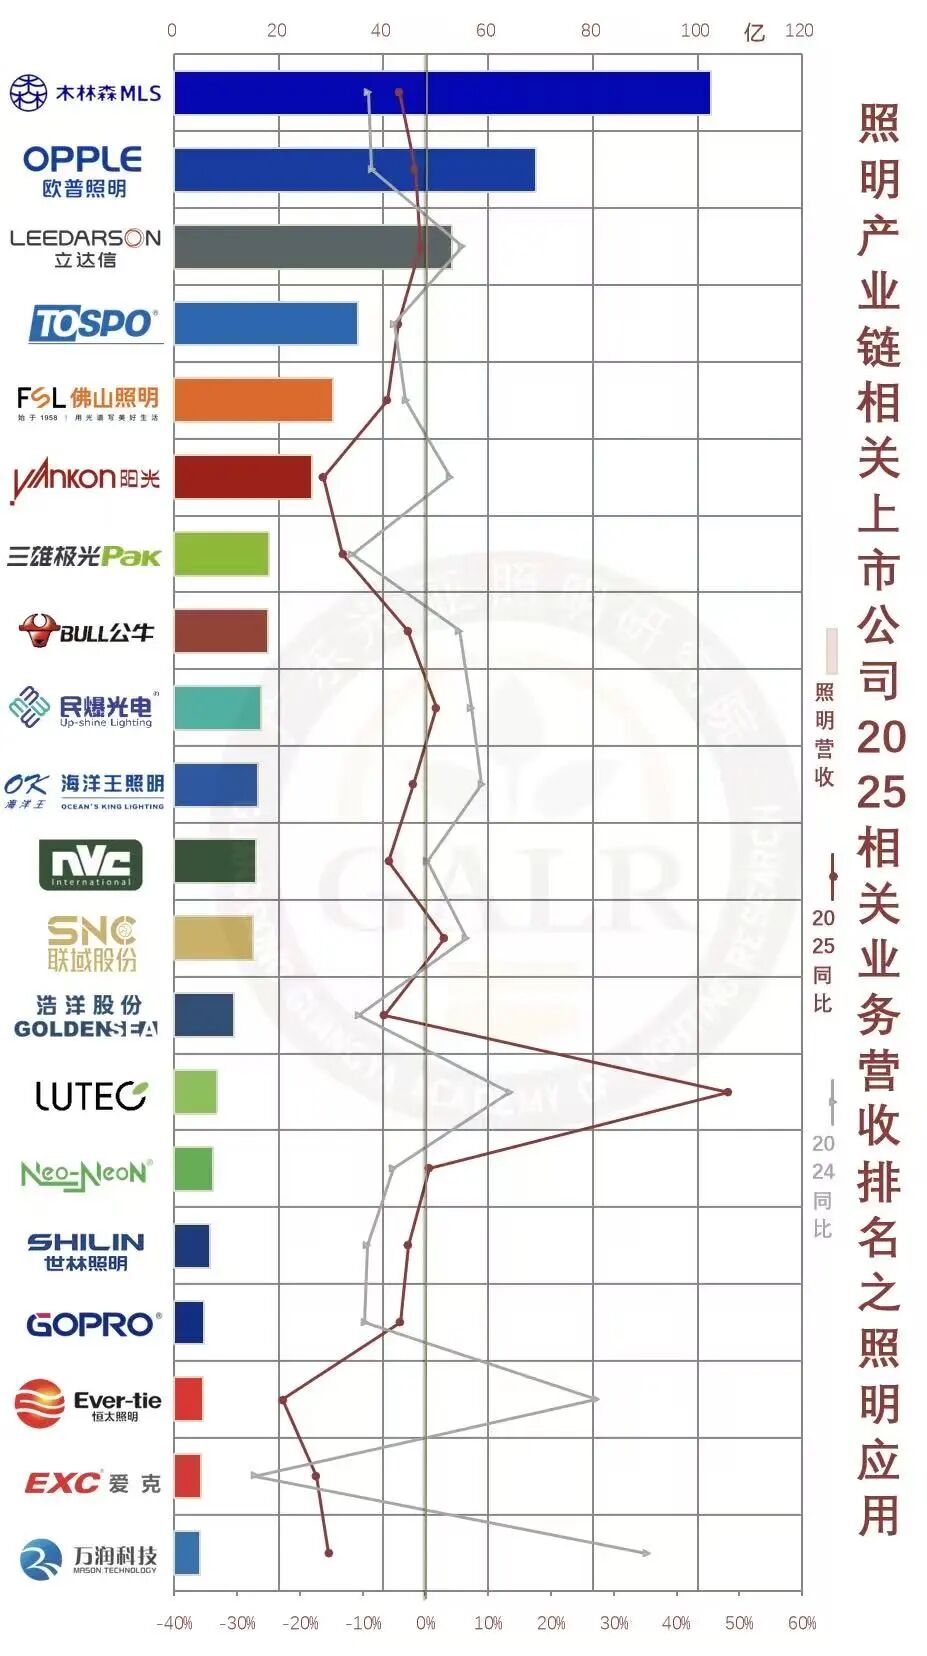
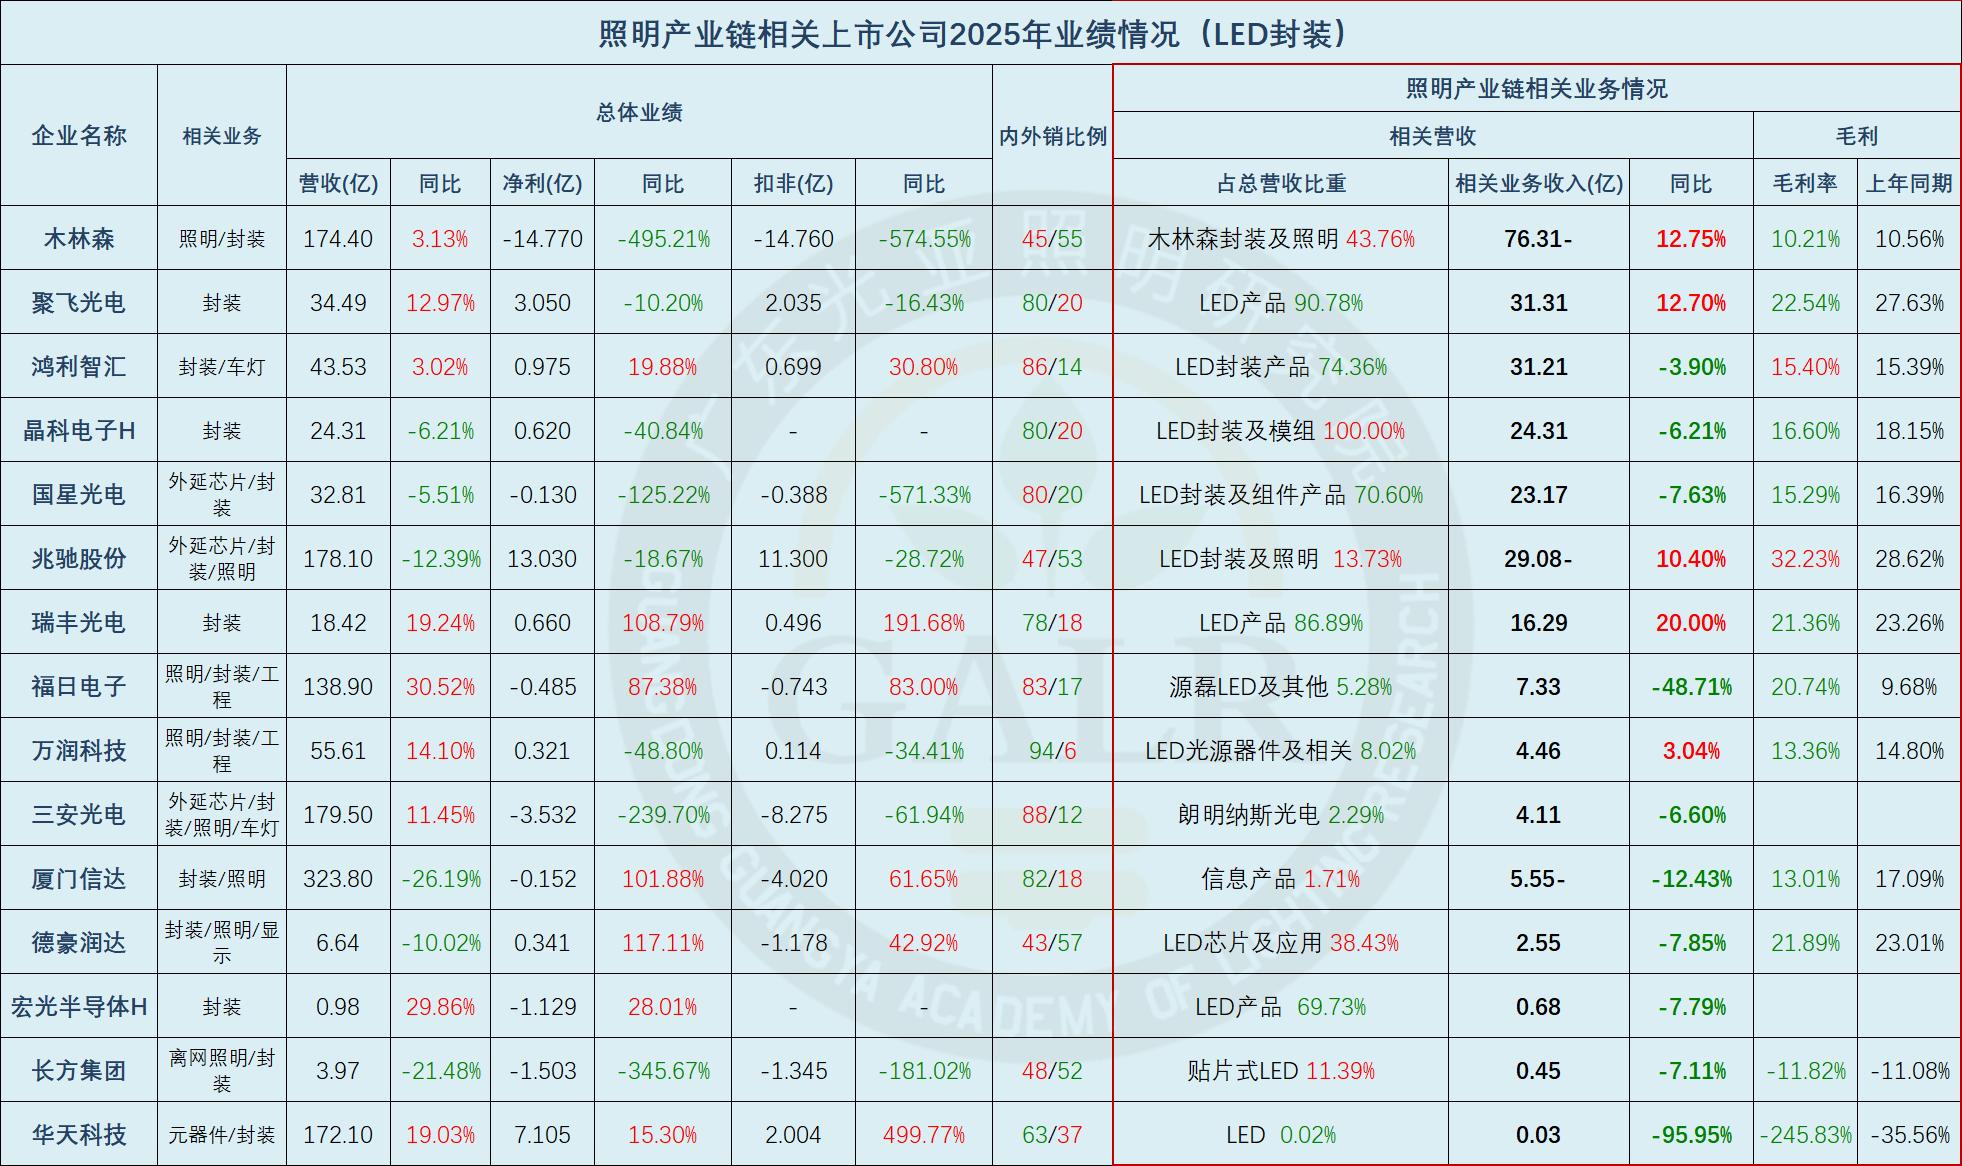
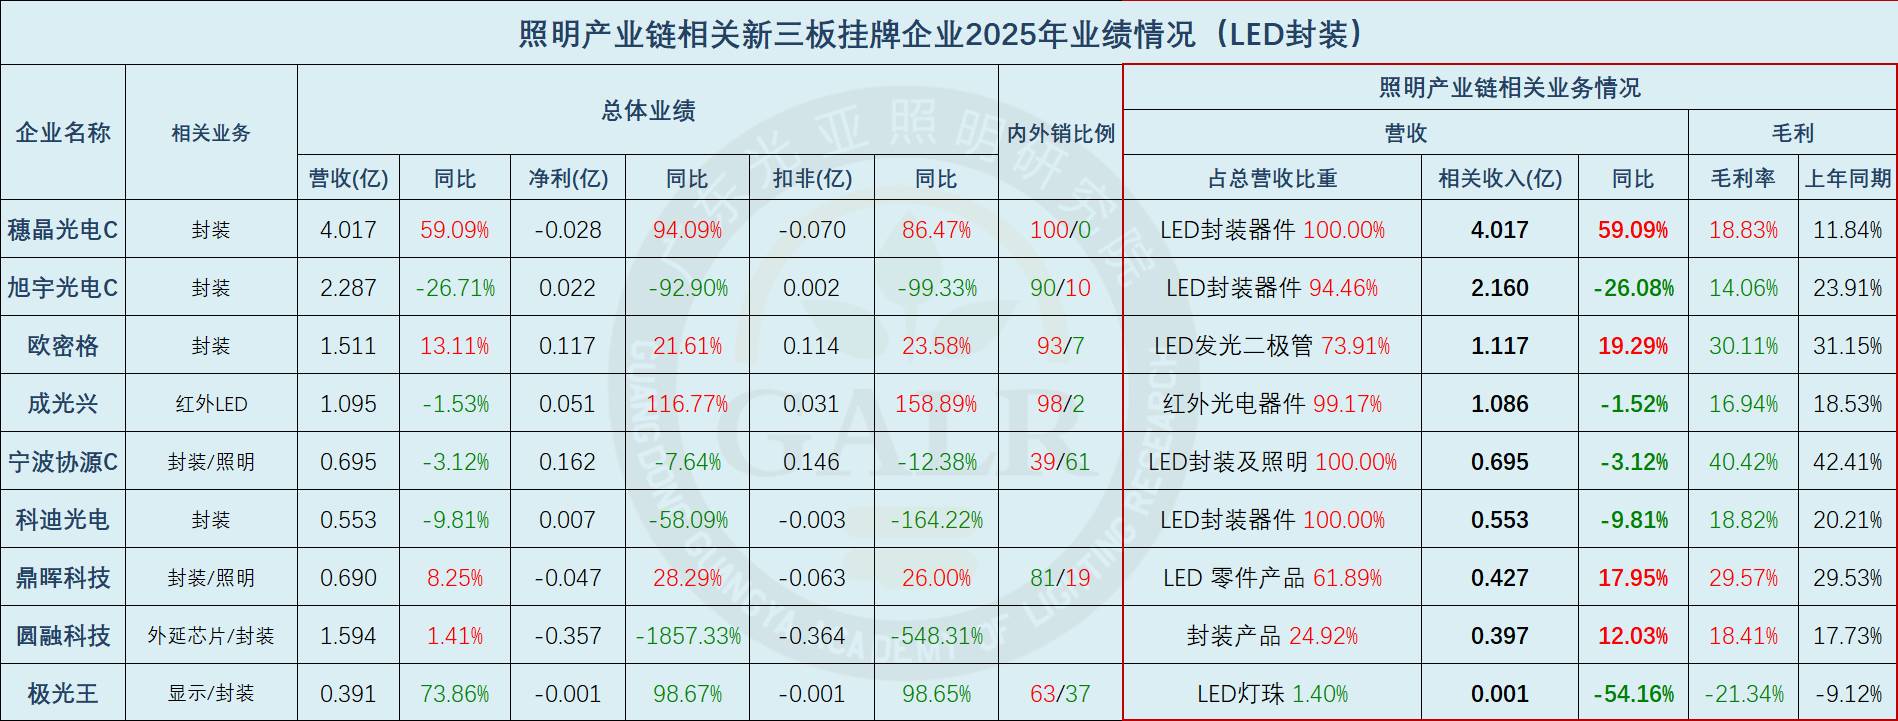
Overall Ranking of Packaging Business (Top 20) (Click to view large image) LED Packaging Sector75% of companies had Revenue growth rates lower than the same period in 2024, and profits were also under pressure.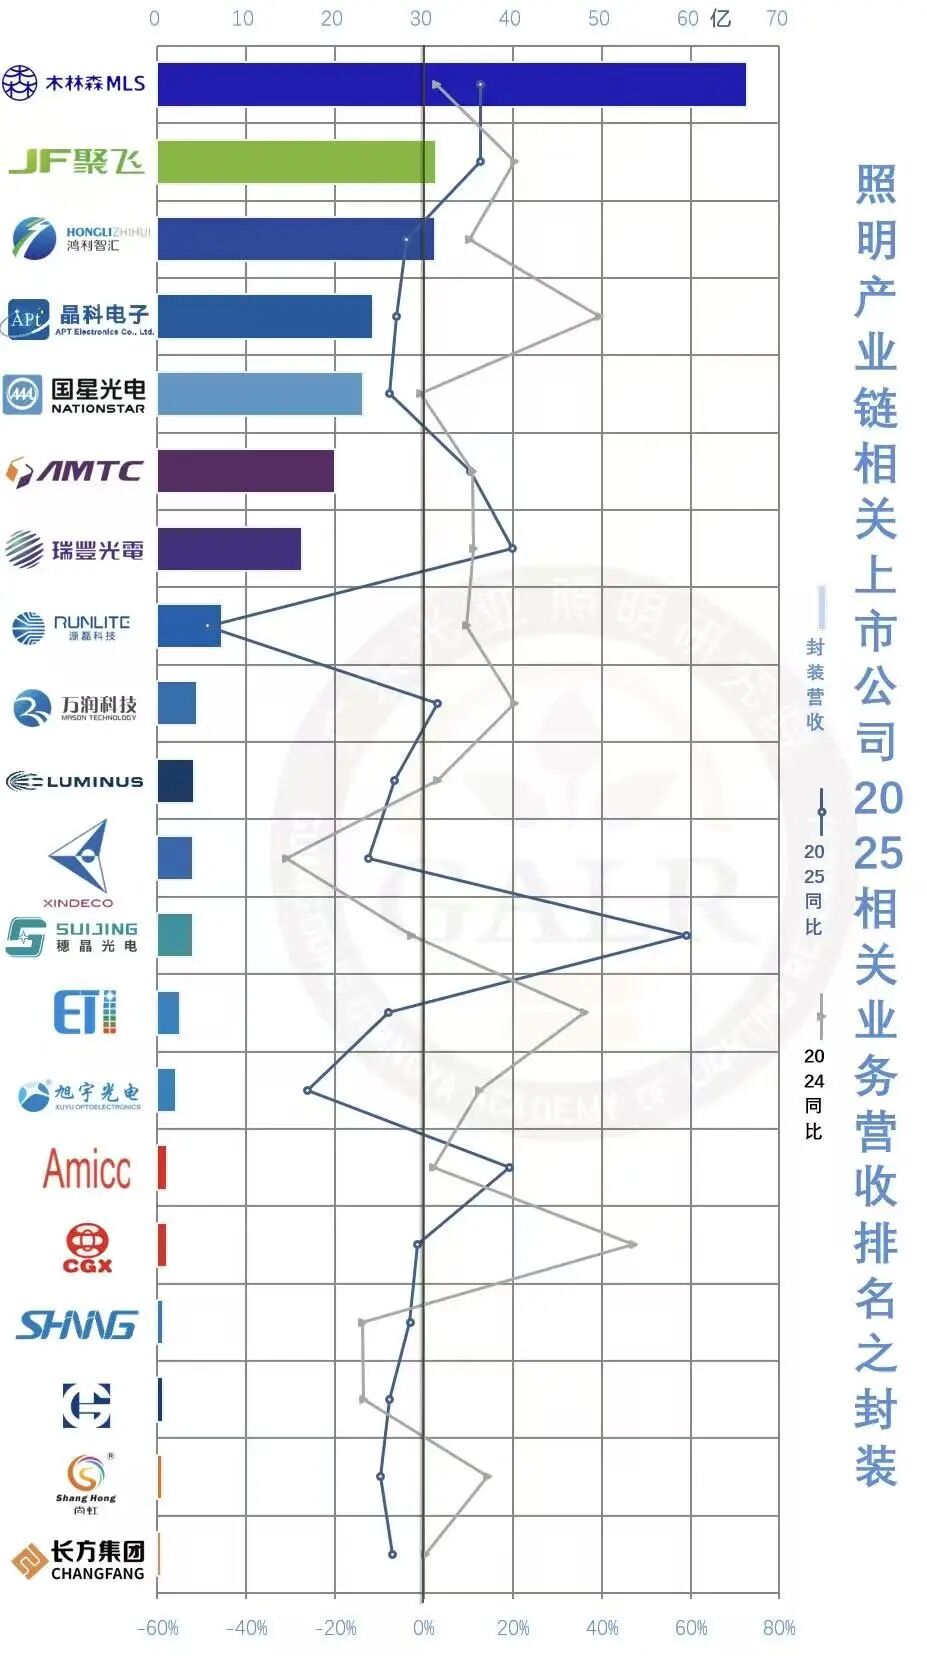
LED Epitaxy Chip Sector Epitaxy Chip Business Overview (Click to view full size) The 'BIG6' landscape in the LED Epitaxy Chip sector remains stable with no changes in ranking; however, compared to the all-red performance of the same period in 2024 , the contraction in downstream demand has clearly transmitted to the upstream. 总共9家上市公司中: Revenue decline in LED epitaxy chip-related businesses was reported by 56% of companies, compared to 0 in the same period of 2024; The share of companies with declining gross profit from LED epitaxy chip-related businesses is 56%, also 0 in the same period of 2024; the average gross margin is 16.7%, down 1 percentage point compared to the same period in 2024; The average capacity utilization rate for LED epitaxy chip-related businesses is 98%, an increase of 2 percentage points compared to the 2024 peak, approaching full production; 整体营收方面,22%的企业营收下滑,44%的企业净利润下滑,44%的企业亏损,较2024年同期(11%、22%、33%)均有所恶化; In terms of labor efficiency, the average labor efficiency ratio for the LED epitaxy chip sector is 1.36 million yuan per person, up 7.9% compared to 2024; the total number of employees decreased year-on-year by 0.9%. The total revenue from the LED epitaxy chip business of the aforementioned nine listed companies amounted to RMB 16.6 billion, representing a year-on-year (YoY) increase of 1.3%. This accounts for over 90% of the entire China LED epitaxy chip industry scale. The industry continues to exhibit highly concentrated characteristics in terms of production capacity and capital. During the same period, sales volume grew by 7.0%, with the upstream, midstream, and downstream segments of the lighting supply chain maintaining a trend where sales volume growth outpaced revenue growth.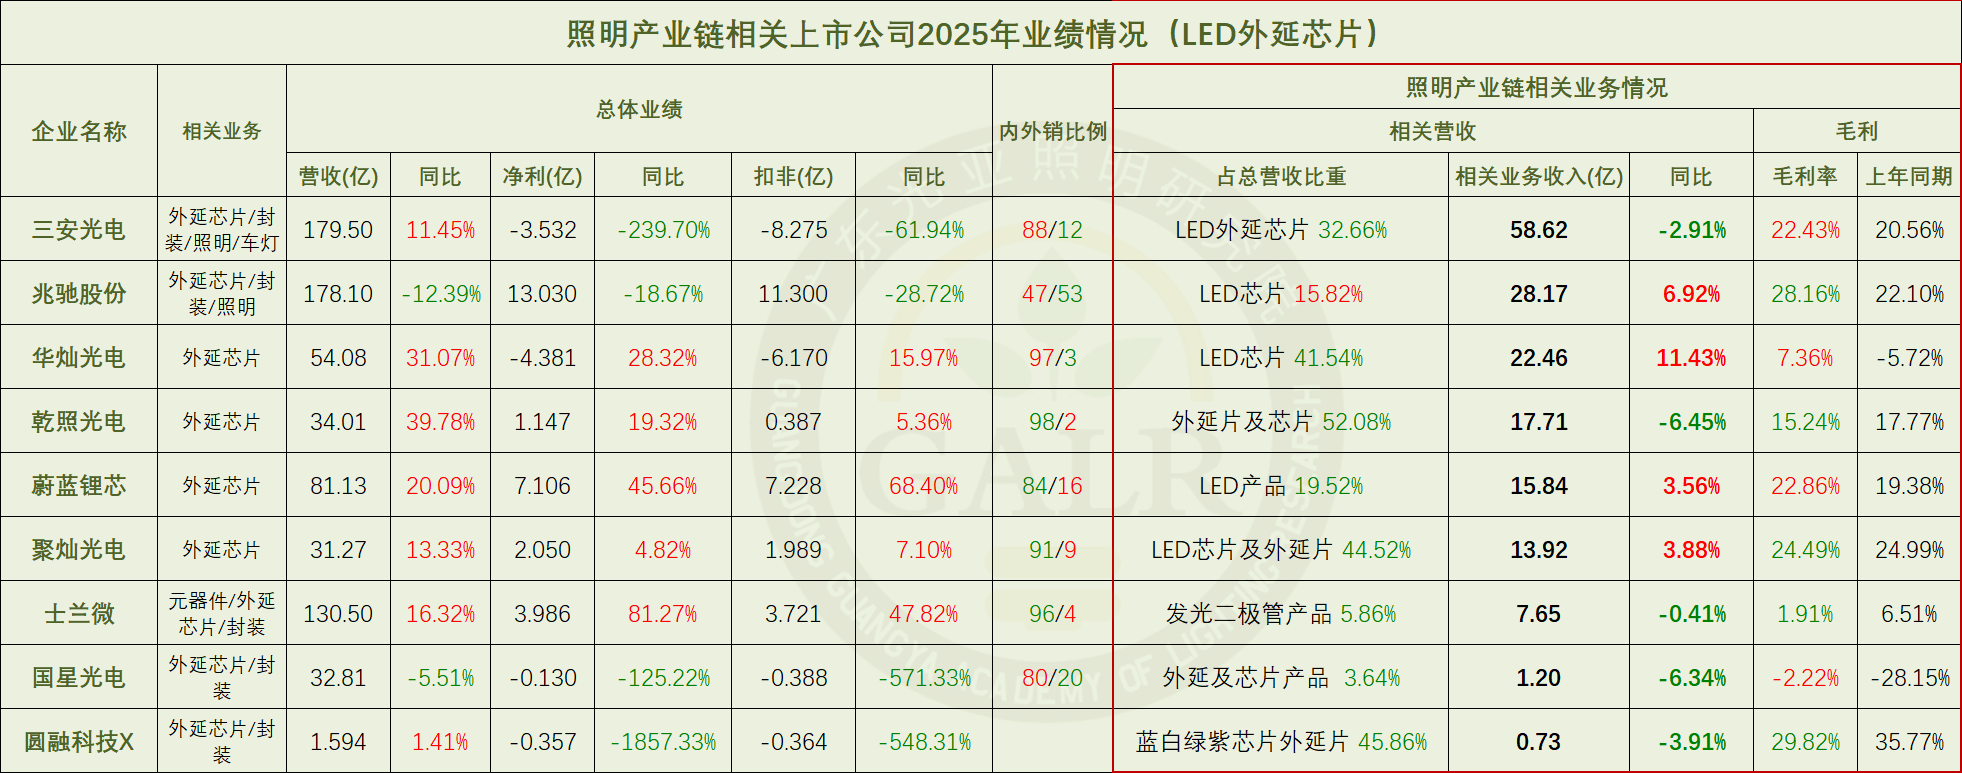
Ranking of epitaxy chip business (Click to view larger image) In 2025, the revenue growth rate of all enterprises in the LED epitaxy chip sector was significantly lower than that of the same period last year.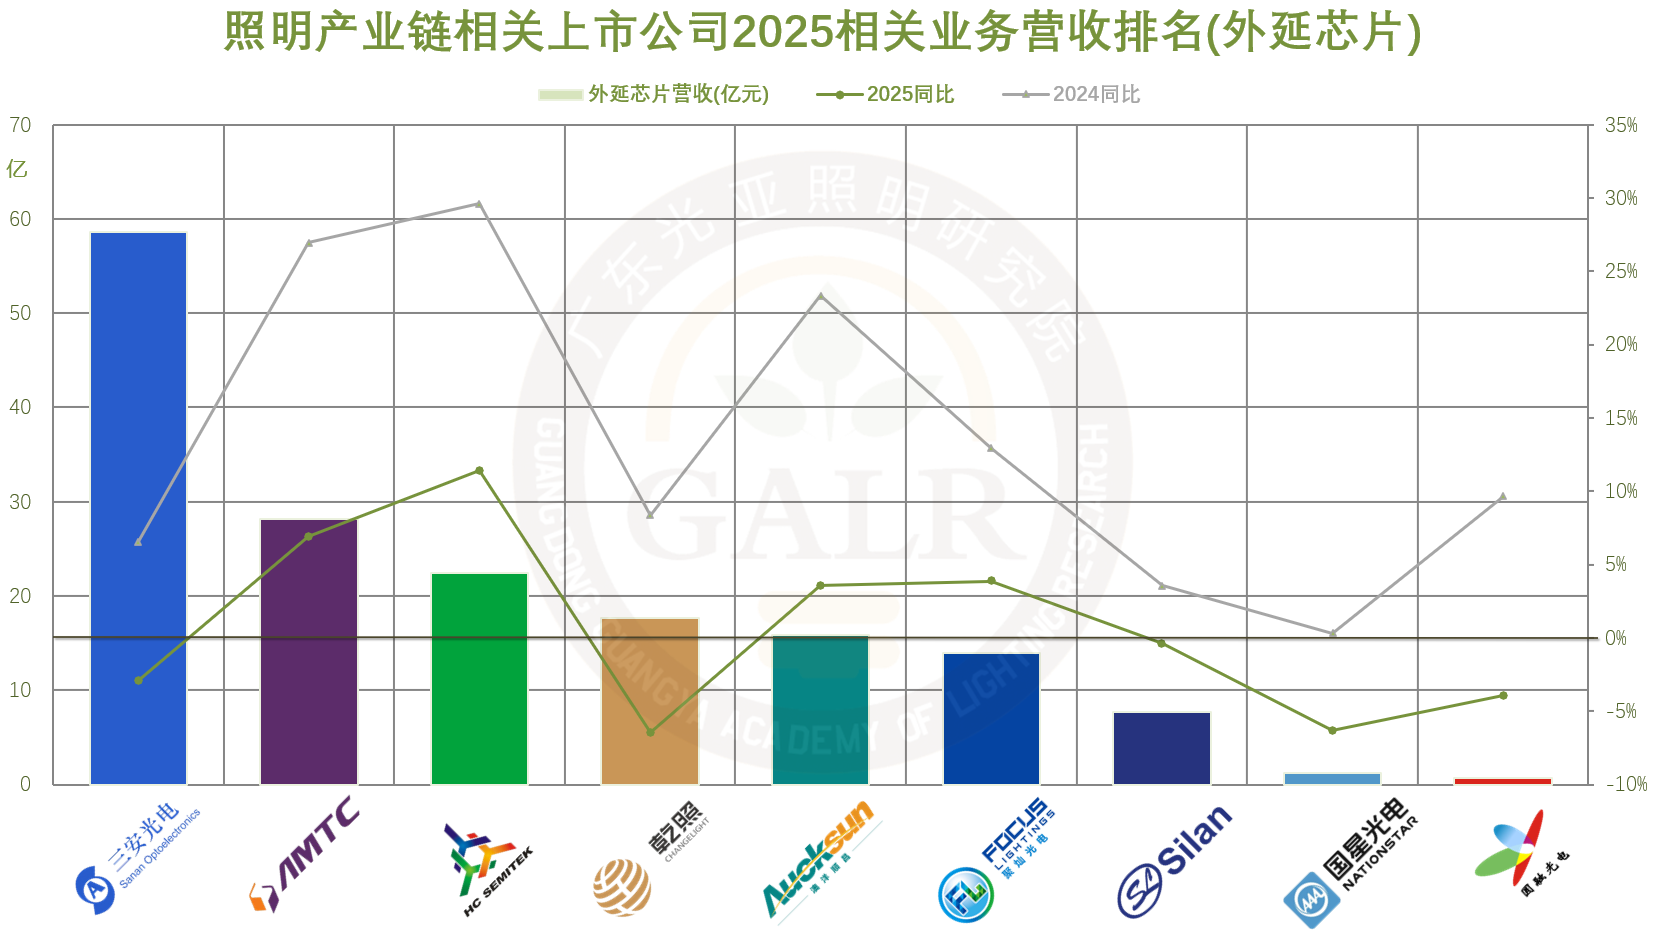
Lighting engineering sector
Lighting Engineering Business Overview (Click to view full size) (Click to view full size ) In 2025, the lighting engineering sector remains in a rational low-level stagnation . Urban renewal, cultural tourism night tours, commercial real estate and other relatively fragmented projects have replaced city-level illumination projects as the mainstream; the old pattern where top-tier contractors ruled the roost is gone forever. Among the total of 18 listed companies (including those listed on the NEEQ): 照明工程相关业务营收下滑的企业占67%,2024年同期为63%;照明工程业务总营收为39亿元,同比下降7.5%。 Enterprises with declining gross profit from lighting engineering-related businesses accounted for 33%, while the figure for the same period last year was 63%; the average gross profit margin was 22.1%, a significant improvement over the 17.5% recorded in 2024; In terms of overall revenue, 33% of enterprises saw revenue decline, 44% saw net profit decline, and half of enterprises reported losses; the situation is generally more relaxed than in 2024. 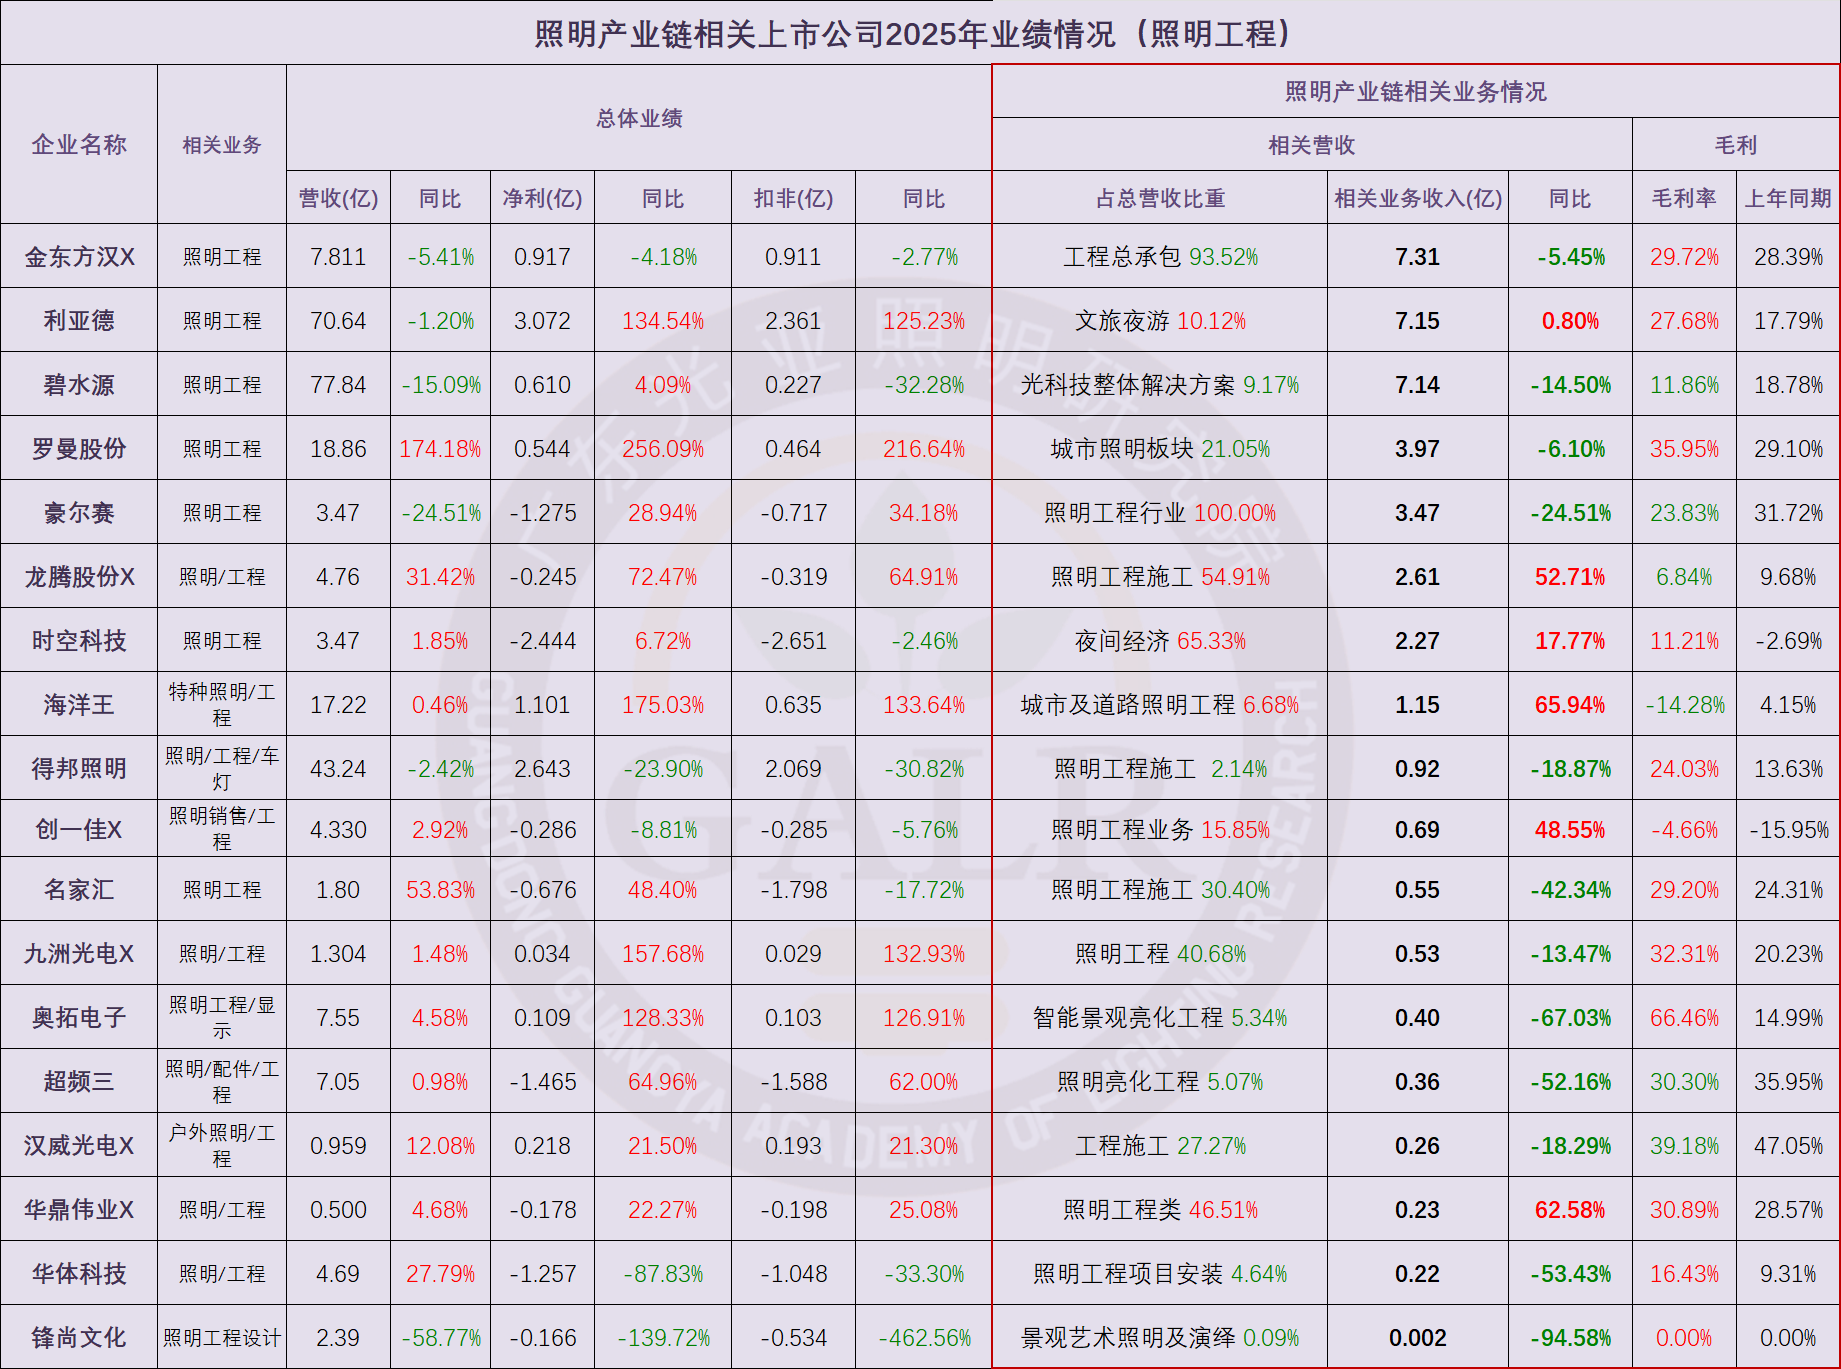
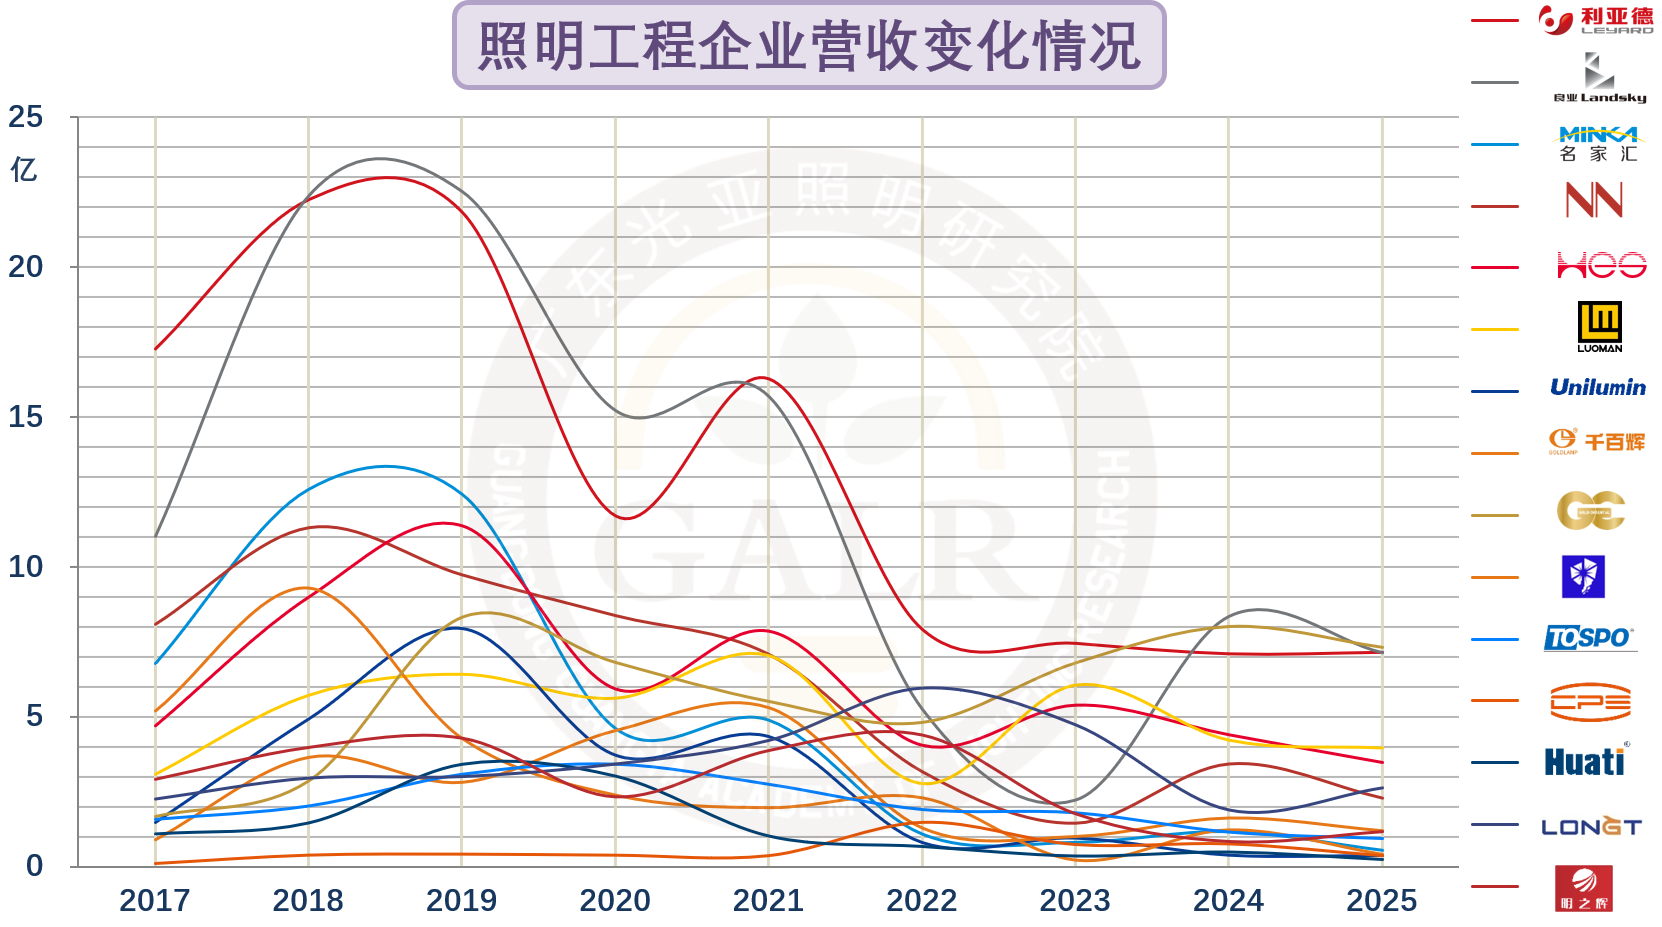
Ranking of lighting engineering businesses: (Click to view larger image) Comparing the revenue growth rate of listed companies in the lighting engineering sector between 2025 and the same period in 2024, performance fluctuations are significant, reflecting the current instability and fragmentation of the lighting engineering market. 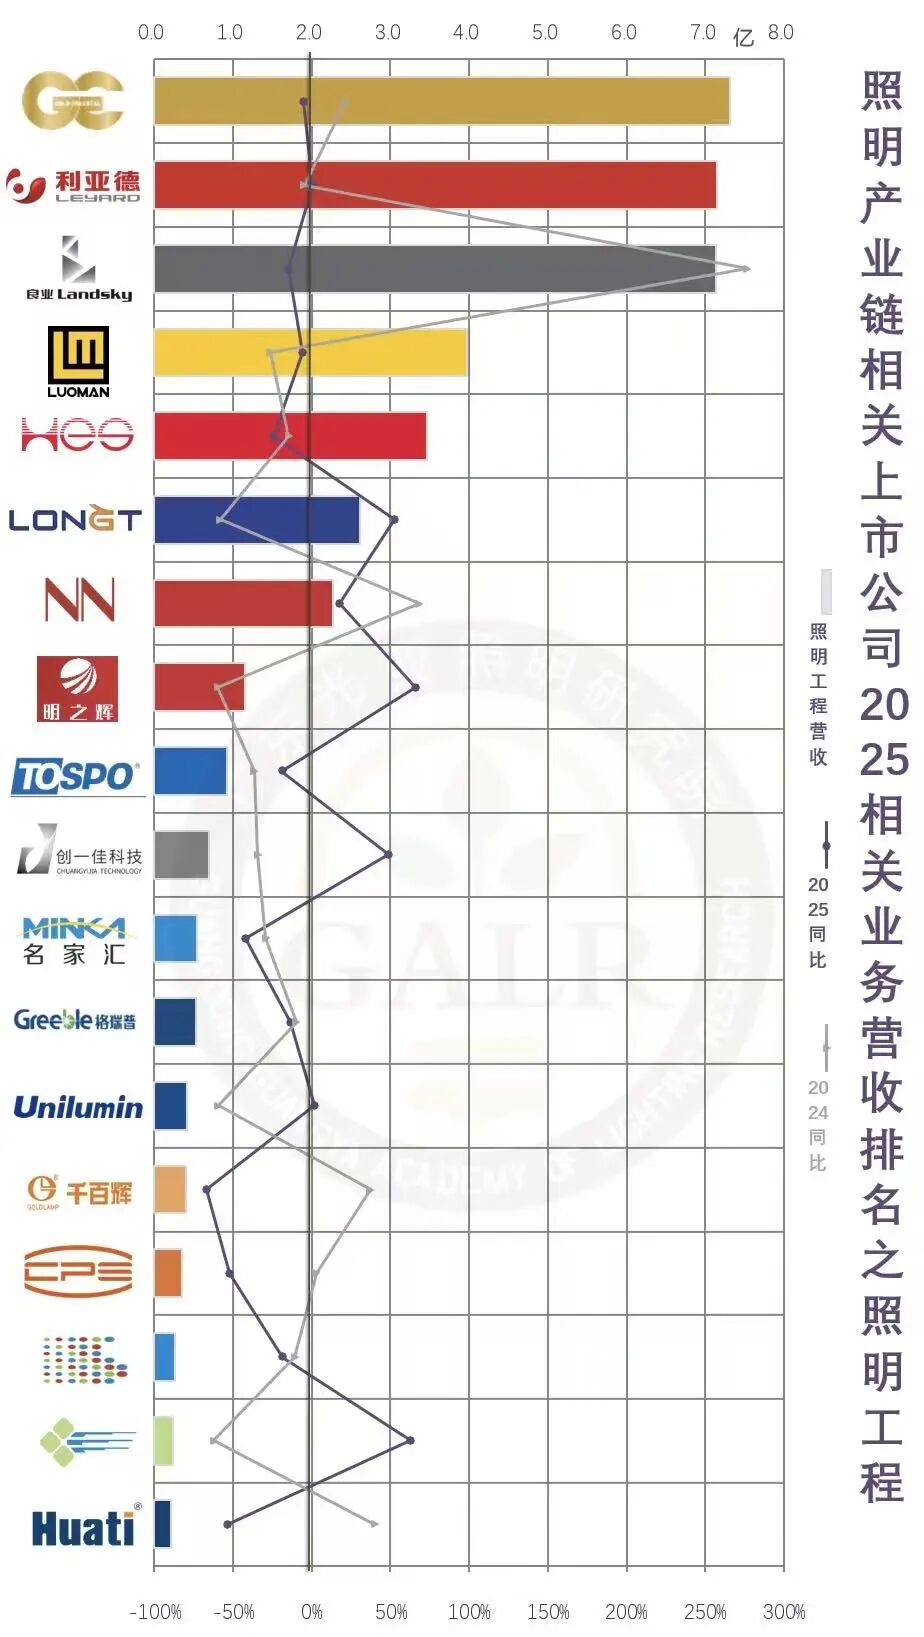
Various supporting sectors
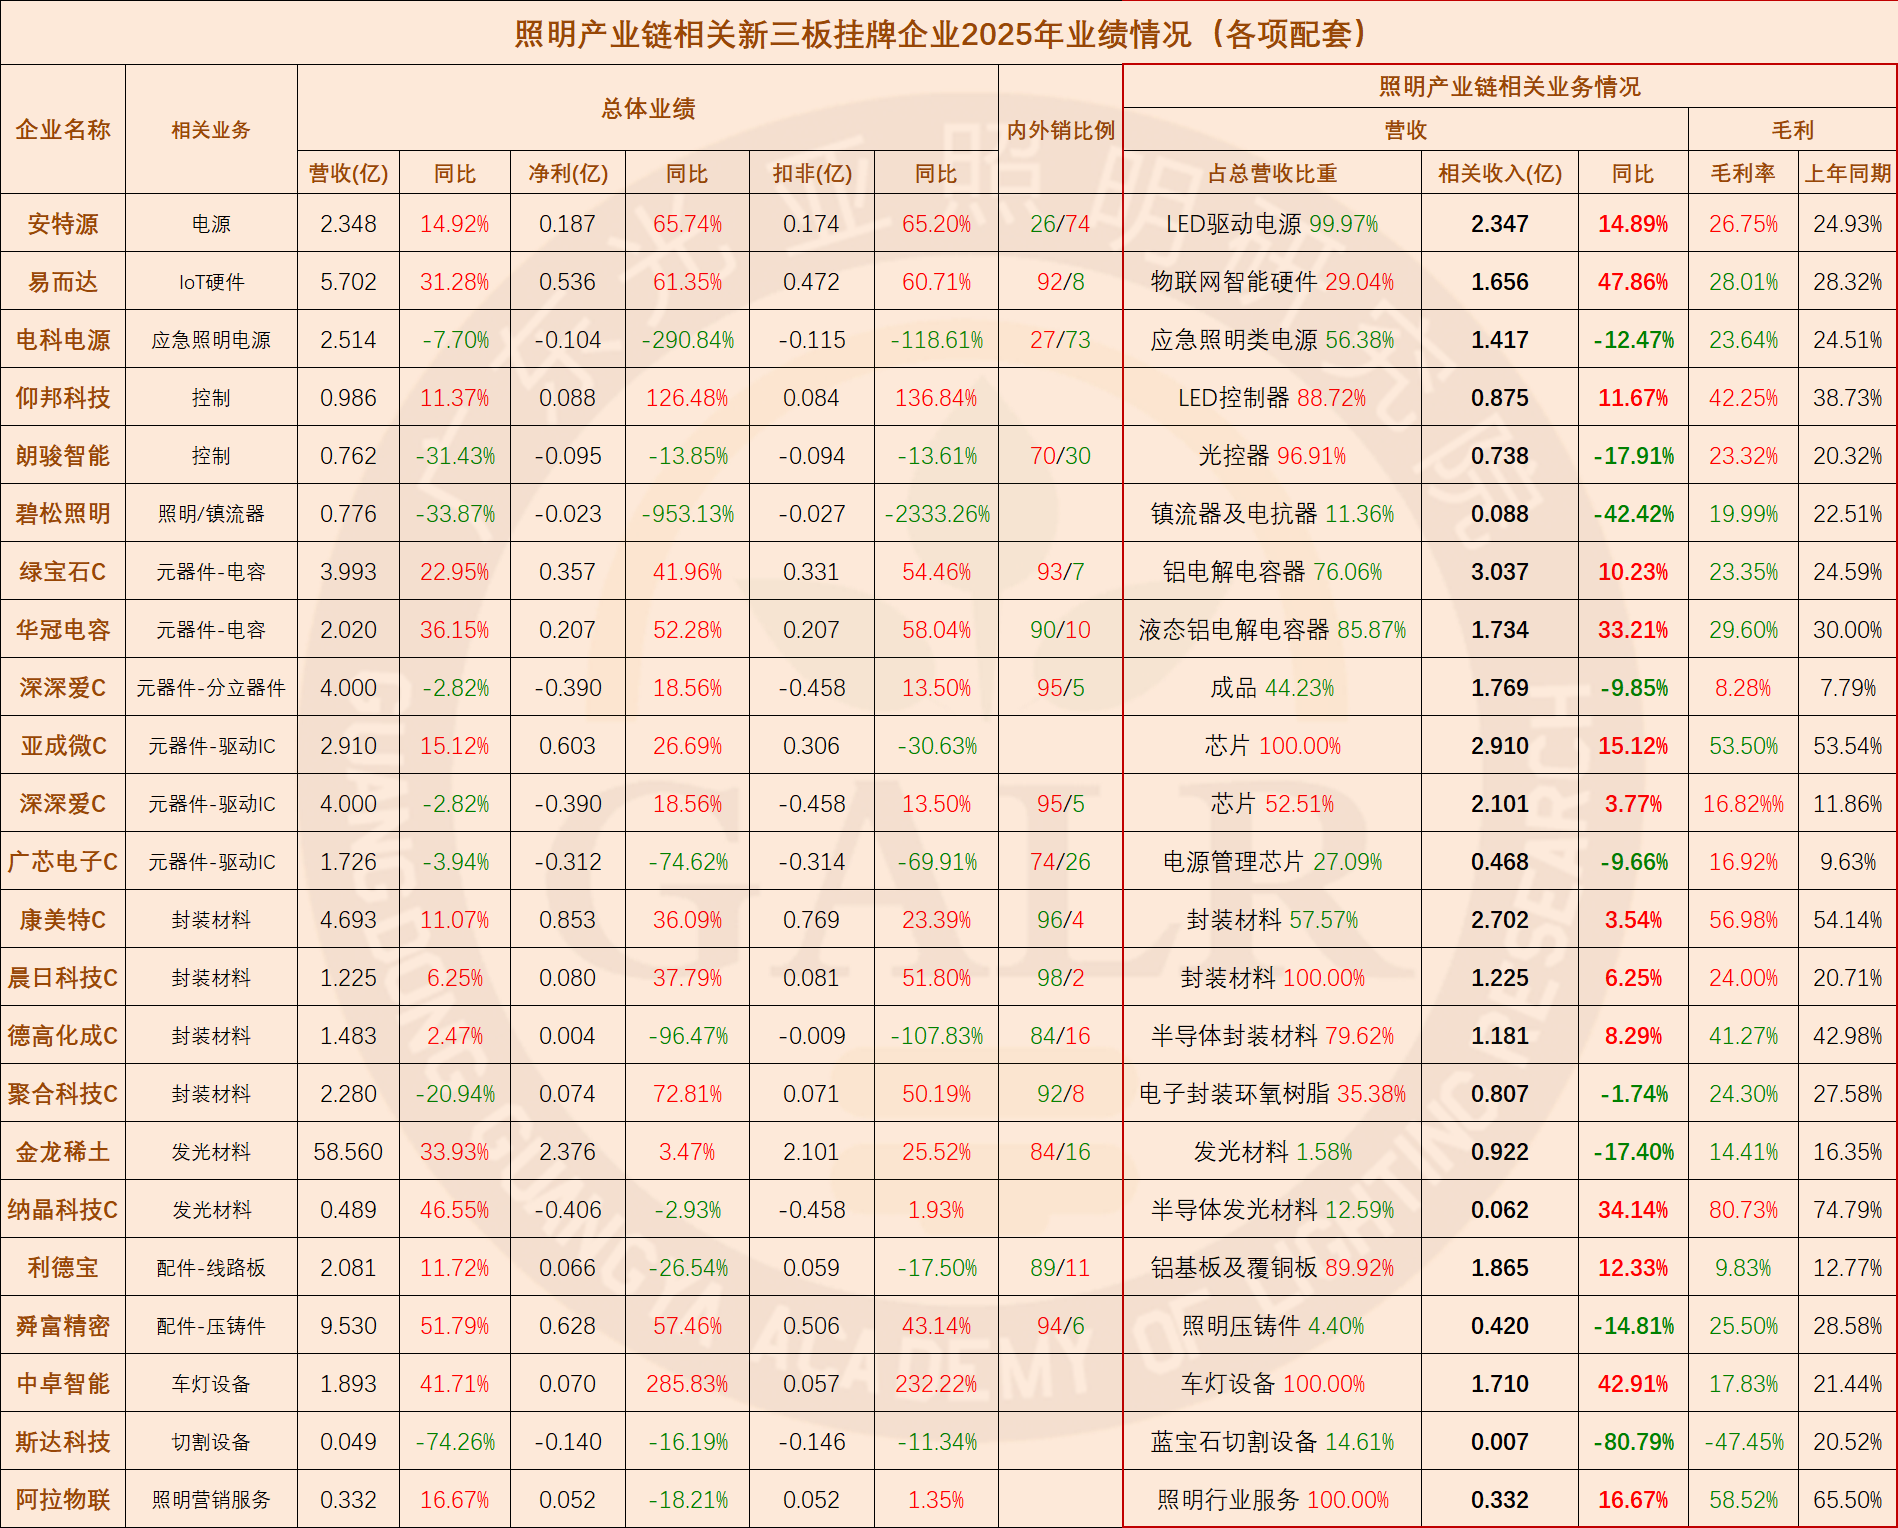
Status of various supporting businesses (Power supply / Raw materials / Components / Accessories / Equipment) (Click to view full size) (Click to view full size) Among the various supporting segments, the power supply/control segment saw mixed revenue performance, with profits under extreme pressure; intelligent solutions emerged as one of the few bright spots. The raw materials segment remained relatively stable, driven by upstream commodity prices. Within the components segment, driver IC companies have continued to suffer significant losses since 2021. The accessories/equipment segment declined overall due to weak downstream demand and deflationary price pressures. Intensifying competition in the mature market is accelerating industry consolidation, with supply chain concentration advancing more rapidly than that of application terminals, yet profitability faces unprecedented challenges. Among a total of 63 listed companies (including those listed on the New Third Board): Enterprises with declining revenue from various supporting related businesses accounted for 44%, an increase of 8 percentage points compared to the same period in 2024: The proportion of companies with declining gross margins in supporting related businesses is 49%, compared to 48% in the same period last year, with an average gross margin of 28.7%, a slight decline of 0.3 percentage points compared to 2024; Regarding labor efficiency, the average labor efficiency ratio for the LED supporting sector is 1.17 million yuan per person, an increase of 2.6% compared to 2024; the total number of employees increased by 1.9% year-on-year. Regarding overall revenue across all supporting sectors, 29% of companies saw revenue declines, 41% experienced net profit declines, and 48% reported losses; while revenue and profit situations were better than the previous year, the proportion of loss-making companies expanded. Overall, among listed companies related to the lighting industry / supply chain, 38% experienced a decline in overall revenue, yet 56% saw a drop in revenue specifically from their lighting industry / supply chain operations, an increase of 16 percentage points year-on-year (YoY), indicating that lighting industry / supply chain business has become a drag on the overall performance of many listed companies; 58% of companies experienced a decline in gross profit margin for their lighting industry / supply chain-related businesses, widening by 5 percentage points year-on-year (YoY); 50% of companies saw a decline in net profit; and 42% of companies incurred losses, an increase of 3 percentage points compared to the same period last year. In short, the current prevailing situation in the lighting Industry is that companies are putting in more effort, but the growth in sales volume can no longer offset cost inflation and the downward price pressure caused by price deflation. While revenue may remain slightly down or show marginal growth, profits have generally been significantly eroded. Striving hard just to stay in place is the core manifestation of involution. In summary, the perceived experience of the lighting industry supply chain in 2025 will be colder than in 2024 . Under the macro environment of low-cycle economy and global restructuring, in the stage of stock competition where both technical increments and market increments face bottlenecks, the lighting industry faces a deep reshuffle. The annual reports of listed companies in the lighting industry supply chain also reveal some cruel truths about the lighting industry: since 2021, the lighting industry has been in a stage of stock competition zero-sum game ; lighting is strong in supply but weak in pricing, and as a mature manufacturing industry, it is no longer a technology-driven industry but a cost-driven industry; LED penetration has reached a bottleneck, with over 85% penetration severely constraining replacement potential; excessively long product life suppresses demand, extending the replacement cycle while increasing channel pressure; structural overcapacity exists, meaning it cannot escape large-scale, low-level, homogeneous repetitive production, triggering vicious price competition; the scissors difference between sales growth and revenue growth continues to widen, with upstream inflation, downstream deflation, and added overcapacity leading to a collapse in product prices; China's supply chain exerts comprehensive crushing force in scale, efficiency, and cost, forcing international giants to contract and withdraw; domestic sales heavily rely on real estate and infrastructure entering a low cycle; foreign trade faces pressures from normalized trade barriers, bloc-based trade systems, and politicized trade issues; new concepts such as smart, healthy, and low-carbon have temporarily failed to become true core growth engines for the industry; regarding the products themselves, lighting can no longer create sustained demand. In this zero-sum game of competition among existing assets, a significant number of enterprises will inevitably exit the market. Enhancing internal capabilities will be the only way for companies to secure their position. This includes: Innovating new technologies, applications, and business models; perfecting internal and supply chain systems; increasing openness to promote products, production capacity, and brands going global; seeking integration, restructuring, and collaboration to weather difficulties; focusing on niche markets and applications; reconstructing operational models and value concepts; optimizing production capacity through marketization; and extending effective business formats based on lighting operations. Data TIPS: According to annual reports of 185 listed companies related to the lighting industry / supply chain in 2025: (99 A-shares, 8 H-shares, 78 listed on the New Third Board) There are 30 state-owned capital-controlled enterprises, accounting for 16% ; There are 34 enterprises that have invested in establishing overseas production capacity (covering Vietnam, Thailand, Cambodia, Malaysia, Indonesia in Southeast Asia; India, Bangladesh in South Asia; and Mexico in Latin America), accounting for 18% ; 46 companies have diversified into cross-sector businesses (including photovoltaics, energy storage, lithium batteries, power generation, computing power, etc.), accounting for 25% . 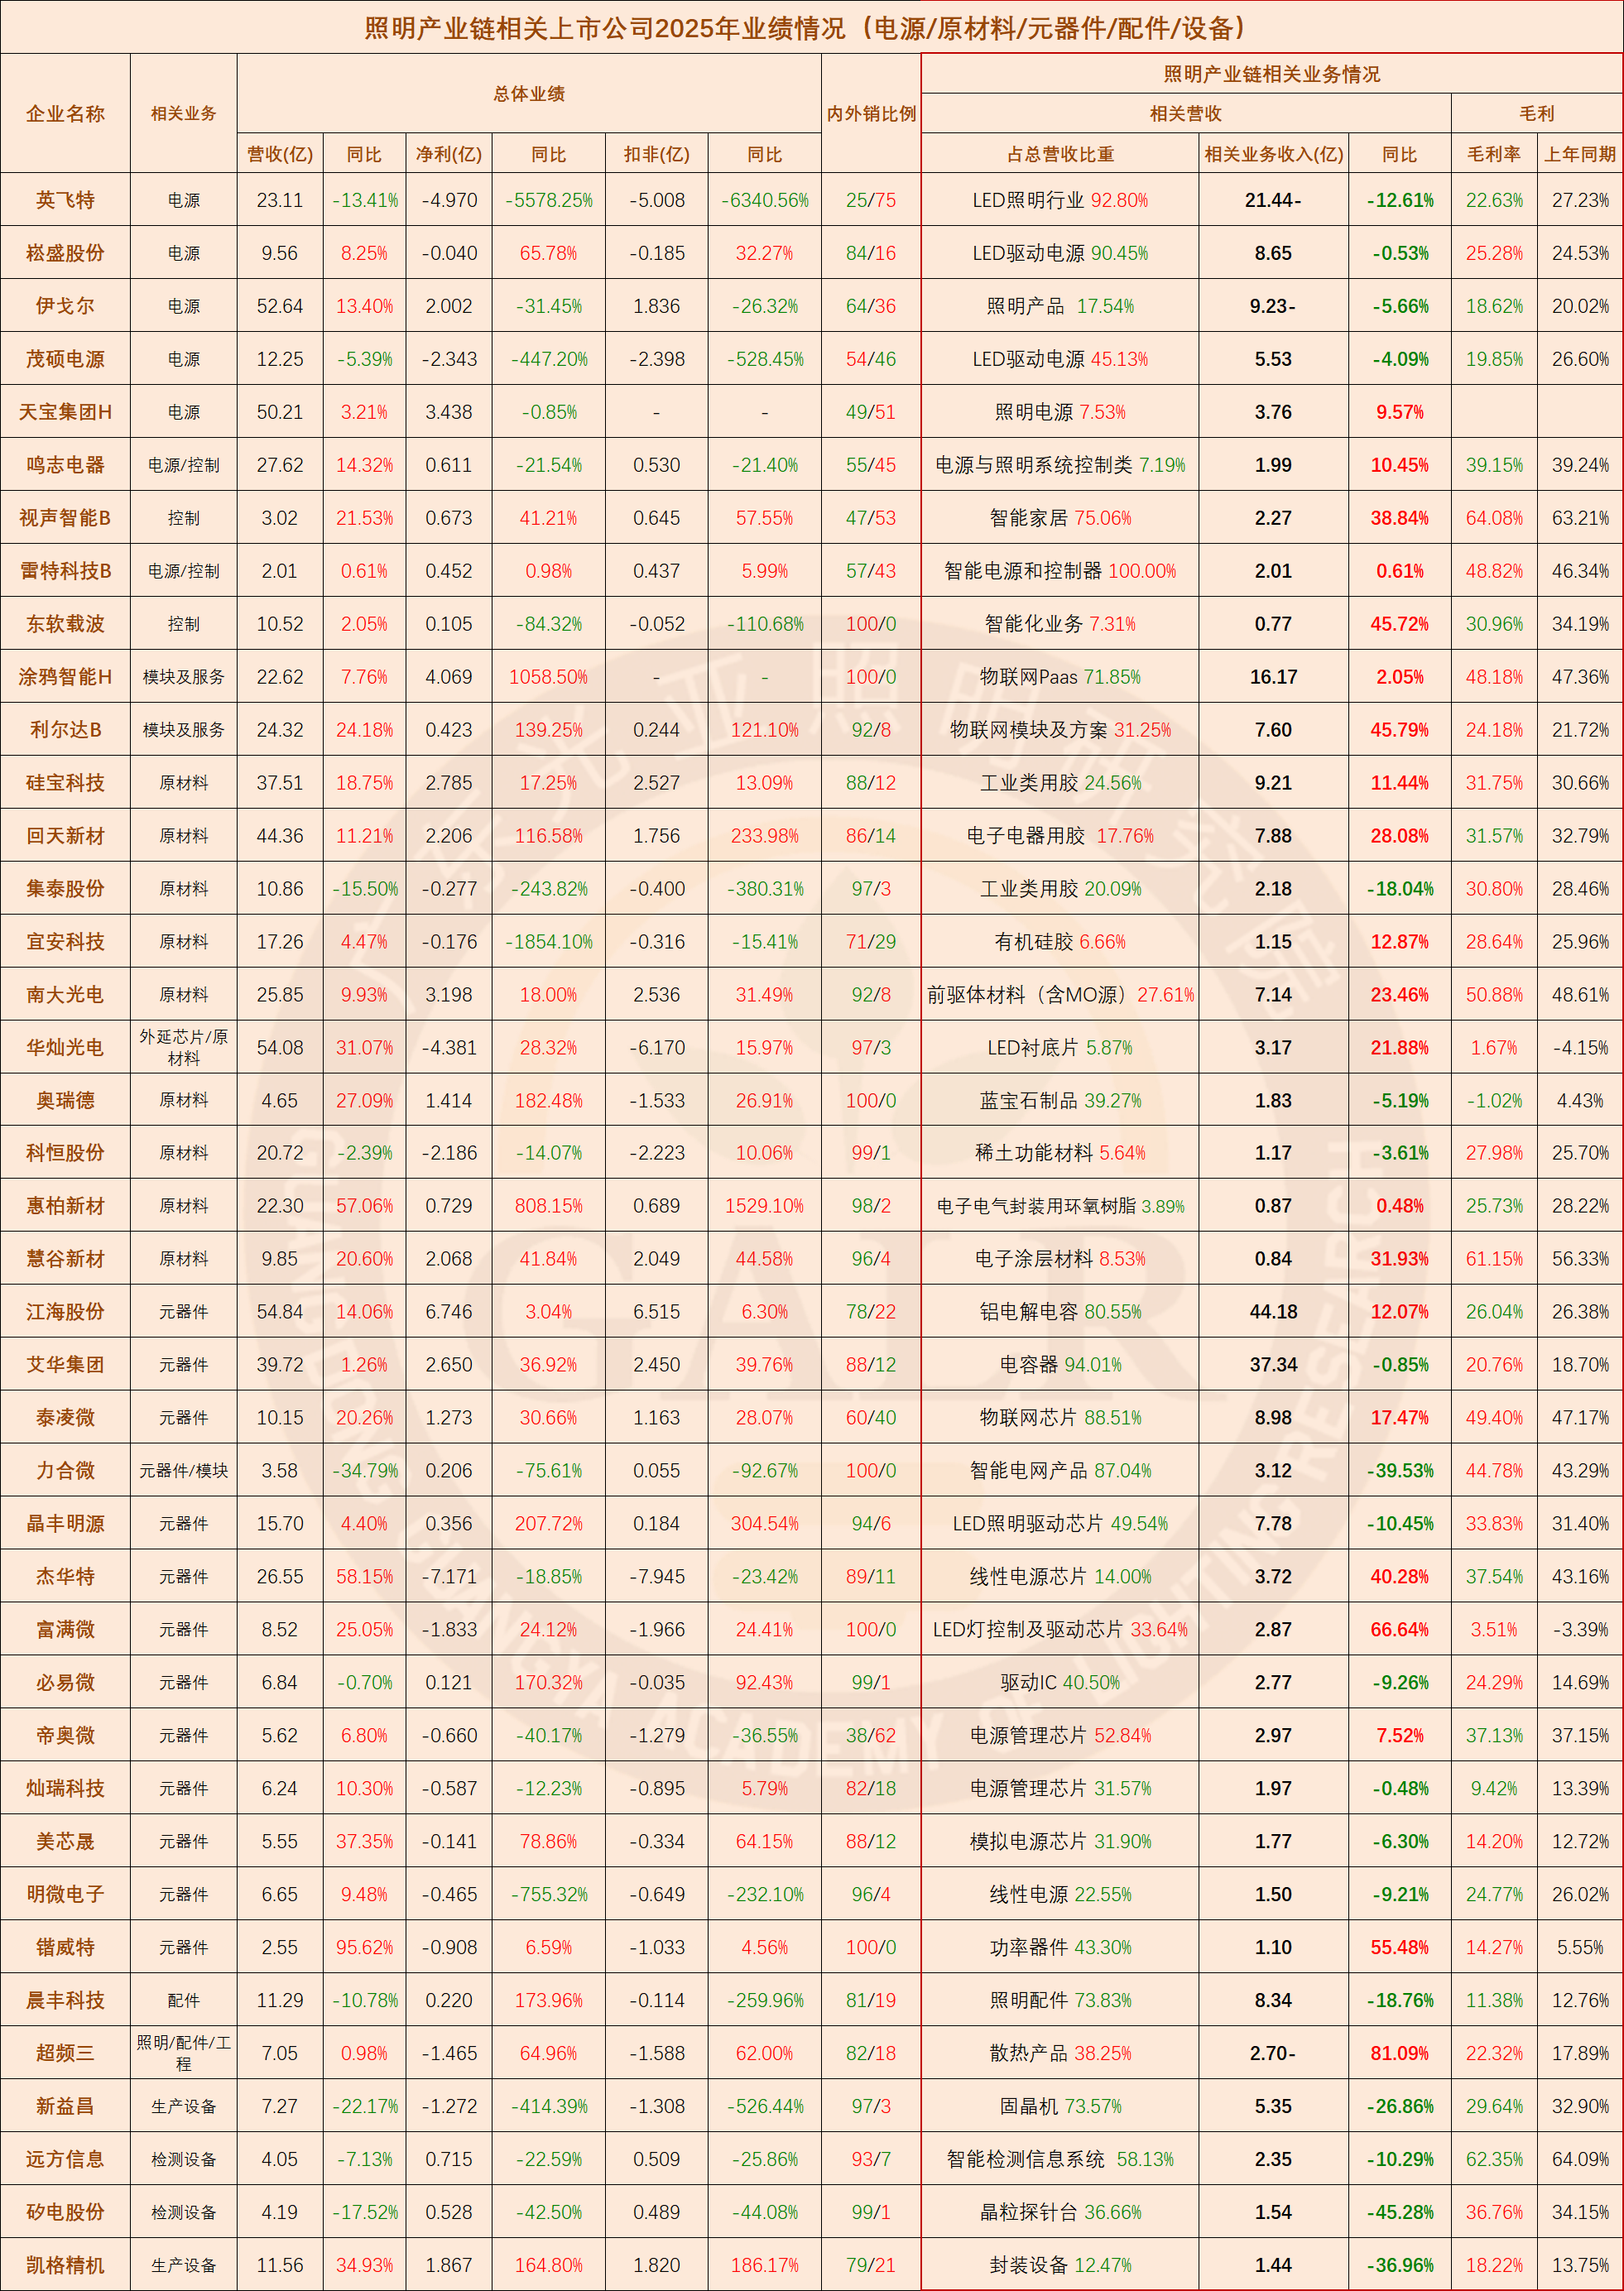
The above article is from the Guangya Lighting Research Institute, authored by Wen Qidong
China Light
The official website of the China Association of Lighting Industry and a full-media platform for the lighting sector. We provide authoritative and timely lighting information while striving to be a growth partner for businesses. From brand promotion and channel expansion to consulting, talent training and participation in standards development, we provide comprehensive professional services to help businesses improve quality and efficiency and jointly advance the high-quality development of the lighting industry.
Business Contacts
仇纯 (Ms.): 158 6155 3579
顾君 (Mr.): 137 7157 5253